Meal prepping can be daunting, and it’s easy to think that all the work won’t pay off or isn’t worth it. However mastering meal prep doesn’t have to mean hours in the kitchen; if you’re smart about it, you’ll find yourself saving money and eating healthier meals in no time. Meal prepping is a great way to take control of your nutrition goals while still having the convenience of ready-made meals — so why not give it a try? In this blog post, we’ll share some tips for how to make meal prepping simple and effective!
1. Set Aside Time Each Week To Meal Prep
One of the best ways to save money on food is to meal prep. Meal prepping involves cooking a large batch of food at once and then portioning it out into individual servings that can be eaten throughout the week. This can help you to save money on both groceries and eating out.
2. Decide What You Want to Eat
The first step to meal prepping is deciding what you want to eat. This may seem like a no-brainer, but it’s important to have a plan before you start cooking. Ask yourself what kinds of foods you enjoy eating and make a list of meals that you would like to prep. Once you have a list of meals, you can begin to plan your grocery list.
3. Choose Your Recipes
Once you know what you want to eat, it’s time to choose your recipes. When selecting recipes, it’s important to consider how long they will take to cook and whether or not you have all of the ingredients on hand. It’s also a good idea to choose recipes that can be easily reheated or eaten cold.
4. Prep Your Ingredients
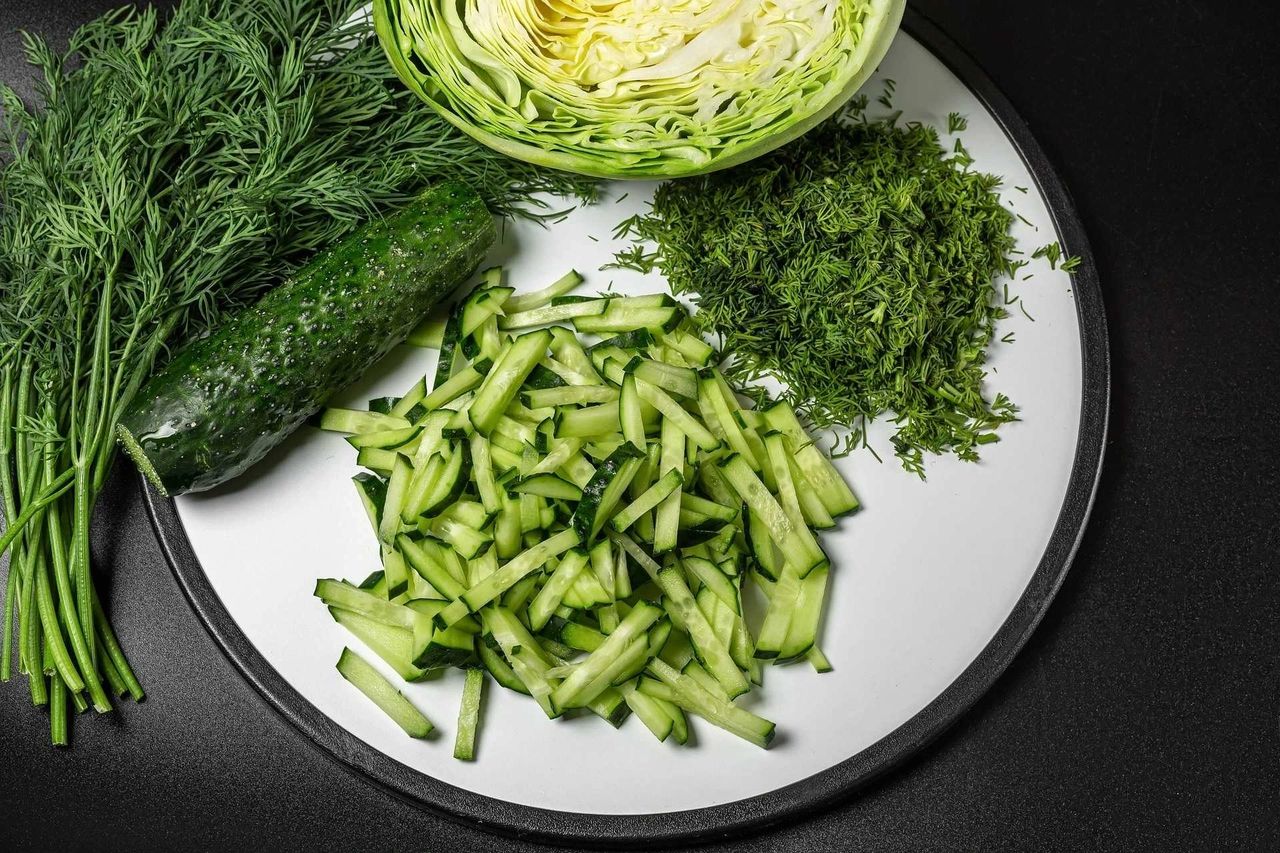
Once you have your recipes chosen, it’s time to prep your ingredients. This means chopping vegetables, cooking meat, and measuring out spices. Prepping your ingredients ahead of time will save you a lot of time when it comes to actually cooking the meals.
5. Cook Your Meals
After your ingredients are prepped, it’s time to cook your meals. If possible, it’s best to cook all of the meals at once so that they are ready to eat for the week ahead. If you’re short on time, you can also cook some meals ahead of time and freeze them for later.
6. Store Your Meals
Once your meals are cooked, it’s important to store them properly so that they don’t go bad. Meals can be stored in airtight containers in the fridge or freezer for later consumption.
Investing in some good storage containers can also help you save money on the skyrocketing prices of food and groceries. Good storage containers will keep your food fresh for longer, which means that you won’t have to throw away as much food.
Discover the benefits of meal prepping – it’s the ultimate time and money saver and it can lead to a healthier lifestyle! You can start small by prepping just a few meals a week, and choosing recipes that are quick and easy to make. Make sure to prep your ingredients ahead of time and cook everything at once for a week’s worth of delicious and healthy food!
Another way to potentially save more money is to find out about the debt relief services Progressive Debt Relief offers. Set up a free consultation today and take the first step towards financial freedom!
*This content must be used for informational purposes only. Progressive Debt Relief does not provide legal, financial or tax advice and the above should not be construed as such.
If you’re looking for fun on the weekend, but don’t want to break your budget, we have some great ideas! In this blog post we’ll look at some of the ways that you can make the most out of each weekend while still being fiscally responsible. There are plenty of activities and adventures that won’t leave you with a hole in your wallet. And we’re not talking about sitting around playing Scrabble or watching Netflix. So, let’s get started – it’s time to find out how to have some serious fun without breaking the bank!
Biking
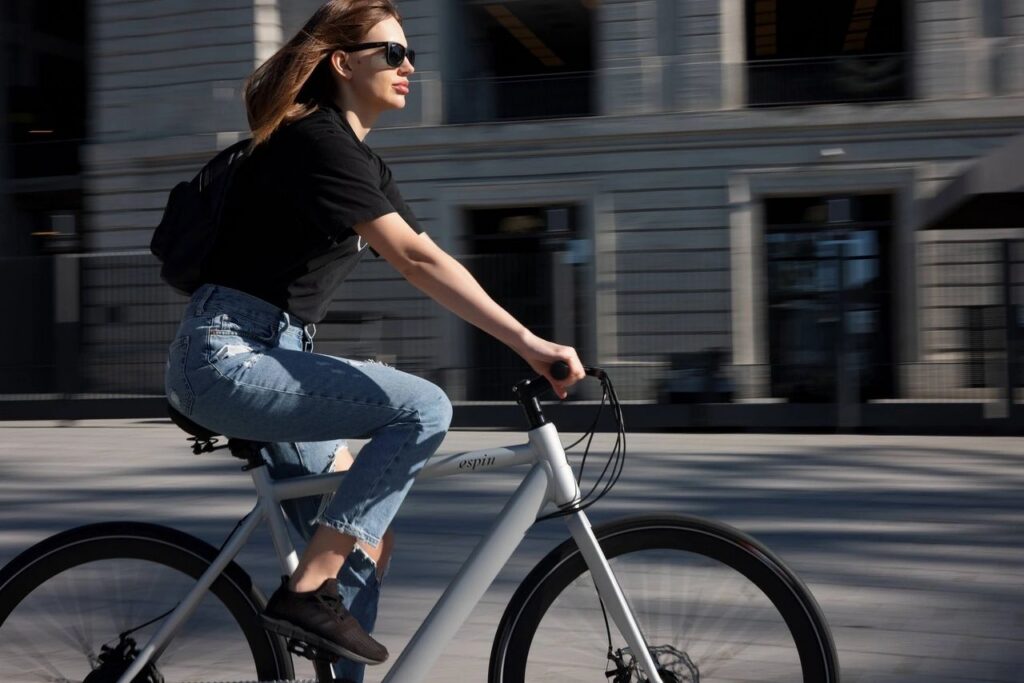
Biking is a great way to get some exercise and fresh air, and it doesn’t cost a thing. There are plenty of biking trails, so you’re sure to find one that’s close to home. And, if you’re feeling adventurous, you can always try one of the new motorized bikes.
Camping
Camping is another great way to enjoy the outdoors without spending a lot of money. You can either camp in your backyard or venture out to a nearby campsite. Either way, you’ll get to enjoy the fresh air and maybe even see some wildlife. Just be sure to pack some snacks and drinks so you don’t go hungry.
Picnicking
Picnicking is a great way to spend an afternoon with friends or family. All you need is a blanket, some food, and a few drinks, and you’re good to go. You can picnic anywhere – in your backyard, at the park, on the beach, etc. – so it’s a great activity for any location.
Potluck dinner party
You provide the house and drinks or dessert, and everyone brings their favorite dish. Make it a themed potluck to add some extra fun – like Italian night or Mexican fiesta.
Have a game night
Dust off those old board games or break out the deck of cards for some good old-fashioned fun. If you’re feeling competitive, make it a tournament with prizes for the winner (and loser).
Local Festivals
There are usually plenty of local festivals happening on weekends during the summer months. These festivals are usually free to attend and offer a great opportunity to experience the local culture. From art festivals to food festivals, there’s sure to be something for everyone!
Go on a hike
If you enjoy nature, look for a nearby trail or park and go for a hike. It’s a great way to exercise and enjoy the outdoors without spending any money. Just be sure to bring plenty of water and the right shoes.
Don’t let tight finances hold you back
Finding ways to make the most of your weekend without breaking the bank can seem challenging, but thankfully there are a variety of options! With a little creativity, you can enjoy yourself without spending too much money. From cooking at home and visiting parks to exploring thrift stores and attending free concerts, there truly is something out there for every kind of interest and budget. So don’t let tight finances keep you indoors– have a look around and take advantage of all the free fun activities that are right around your backyard!
Explore Progressive Debt Relief
Progressive Debt Relief is a pioneer in resolving payday loans however, we are a lot more. With the ability and experience to settle other forms of unsecured debt, PDR’s purpose is to improve your quality of life by offering sound financial solutions to fit your individual needs. Through counseling, budget recognition and monetary awareness, Progressive Debt Relief is determined to ensure the client has all the tools necessary to avoid any financial distress in the future. The result establishes a debt-free life with peace of mind and a calming confidence that comes with progress. To learn more please visit https://progressivedebtrelief.com/or call 877.590.1847 to schedule a free consultation.
*This content must be used for informational purposes only. Progressive Debt Relief does not provide legal, financial or tax advice and the above should not be construed as such.
If you’re like most people, it can be difficult to keep track of your finances. You might think that creating a budget means giving up all the fun in your life and living on beans and rice – however this simply isn’t true! With careful planning and vigilance, creating a budget for yourself doesn’t have to feel like punishment. Instead, with the right plan in place, you can gain financial security, increase your savings potential, and reduce stress about bills. In this blog post we will explore how to make a budget that works for you so that you can work towards achieving your desired financial future.
Determine your income.
The first step to creating a budget is to determine your income. This includes all money that you receive on a regular basis, such as your salary, tips, child support, alimony, and any other forms of income. It’s important to be as accurate as possible when determining your income, as this will be the foundation of your budget.
Track your spending.
The second step is to track your spending. For at least one month, write down everything that you spend money on, including groceries, rent, utilities, transportation, entertainment, and any other expenses. This will give you a good idea of where your money goes each month and where you may be able to cut back.
Set up a budget.
Once you have determined your income and expenses, you can set up a budget. Start by creating a list of all your necessary expenses, such as housing, food, transportation, and utilities. Then, add up all of these expenses to see how much you need to spend each month just to cover the basics. Consider using a tool such as excel or Google sheets to make it easier to monitor.
Make room for savings and debt repayment.
After you have covered your necessary expenses, you can start setting aside money for savings and debt repayment. Begin with small goals, such as saving $50 per month or paying $100 extra towards your credit card debt each month. As you get more comfortable with your budget, you can increase these amounts.
Review and adjust your budget regularly.
It’s important to review and adjust your budget regularly, ideally once a month, to make sure it is still realistic and achievable. As your income or expenses change, you may need to make some adjustments to ensure that you are still able to meet your financial goals.
Creating a budget for yourself does not have to be a complex process. By following these simple steps, you can budget for yourself and begin regular saving habits that will help you create the financial future you desire. It is important to remember that the key to success with any kind of budgeting is consistency and self-discipline. Don’t be too strict on yourself if you find it difficult to stick with your plan – take small, incremental steps towards achieving your desired financial future over time.
Help is available
If you need assistance with debt relief, keep in mind that Progressive Debt Relief is available for free consultations, so do not hesitate to reach out at 877-590-1847 or to learn more please visit https://progressivedebtrelief.com/ or call 877.590.1847 to schedule a free consultation.
*This content must be used for informational purposes only. Progressive Debt Relief does not provide legal, financial or tax advice and the above should not be construed as such.
Credit card balance transfers can be a great way to lower your interest rate and pay off debt faster. However, they also come with some drawbacks that you should consider before making the decision to move forward. By understanding all of the drawbacks associated with credit card balance transfers, you can make an informed financial decision that is best for you.
When considering making a credit card balance transfer, it’s important to consider how long you plan on having debt in order to determine whether or not such a move would be beneficial in the long-term. Most providers offer promotions that include low interest rates, or no payments, for anywhere between 6 months to 2 years. After this promotional period ends, regular interest rates will apply, and regular payments must begin being made otherwise penalties start accumulating at alarming levels.
KEY TAKEAWAYS
consider how long you expect to carry the debt
be careful not to use balance transfers as ATM machines
know the interest rates/fees once the promotional period ends
One potential drawback of transferring a balance from one credit card to another is that it could temporarily bring down your overall credit score. The score will eventually go back up once the new loan has been paid off, but in the interim period, it may cause problems when trying to get another type of loan or other types of financial services approved.
Another consideration are the fees associated with a balance transfer. Many banks charge a % on each transferred amount and this fee can add up quickly if transferring large amounts of debt from multiple cards. Additionally, depending on the provider, you may have to pay an annual fee once the promotional period ends– which will further increase your overall cost of borrowing money.
It is important to keep in mind that using balance transfers for paying off debts is not necessarily going to solve all of your financial problems. If you have accumulated other types of debt in addition to credit cards, such as student loans or medical bills, then this approach might be a temporary band aid and not an effective long term solution.
Another potential issue with a credit card balance transfer is that lenders often charge fees and high interest rates once the promotional offering period ends. This makes it important to research different companies so you can assess which ones offer the best terms and conditions before committing yourself to a balance transfer you may regret.
An additional risk is getting into too much debt. A frequent mistake people make when transferring balances between cards is not reducing their spending. It is easy to end up continuing to accumulate more debt even after transferring existing debts over. It’s therefore important that you have a clear plan in place before making a balance transfer– don’t use it just because you think you will have more money to spend.
Also take note if any specific introductory or promotional offers become invalidated due to late payments or payments being missed which can result in an immediate high interest rate on your outstanding balance.
Final thoughts
A credit card balance transfer can be a way to reduce high interest payments and manage debt more efficiently. However, it is important to weigh both the potential benefits and drawbacks in order to make an informed decision about whether or not a balance transfer is suitable for your situation. With proper research and careful consideration, you should be able to make the best financial decision for yourself and your family. If you find yourself struggling with credit card debt, or any unsecured debt, you can always contact Progressive Debt Relief 877.590.1847 for a free consultation.
*This content must be used for informational purposes only. Progressive Debt Relief does not provide legal, financial or tax advice and the above should not be construed as such.
Getting a tax refund may make you feel like you hit the jackpot! You will surely be thinking about how you are going to put that extra cash to use. While the most tempting option is to splurge and purchase items which could be considered ‘wants’ rather than ‘needs’, it’s important to develop a plan for how to use your refund most effectively.
If you have debt weighing you down, then your gut instinct might be telling you to pay off what you owe. That feeling is totally valid – getting rid of debt should definitely be a priority in order to achieve financial freedom. However, before applying your tax refund toward outstanding debts, there are some things worth considering. In this post we’ll explore some strategies for paying off debt with your tax refund.
Why Paying Off Debt Can Be A Smart Financial Move
If you are considering using your tax refund to pay off debt, it can be a smart financial move. When you pay off debt, you are essentially paying yourself back with the interest you are saving. This can help to free up money in your monthly budget and can also help to improve your credit score.
While utilizing your tax return to pay off debt can be an effective way of getting ahead financially, it’s important to consider the bigger picture. Before allocating those funds, ensure you are up-to-date on any overdue bills and you have set aside money for emergency expenses.
Calculate All Your Outstanding Debt
Once you know you are receiving a tax refund and how much money you will be receiving, you will need to calculate how much debt you have. List all your debt on a spreadsheet, including the amounts and the interest rate you are paying for any outstanding credit card balances, medical bills, personal loans, etc. Once you know how much debt you have, and the interest you are paying, you can decide how much of your tax refund you would like to use to pay it off.
Create A Plan
Before allocating your tax refund to debt payments, make sure you have taken care of any overdue bills that need to be paid off as soon as possible. Additionally, if you do not have an emergency fund remember to save some money to have it available for emergency expenses that might arise.
Once you have a grasp on your debt, and how much of your refund you plan to apply to it, you can create a plan for how to apply it.
Make sure your plan includes specific goals—like which debt you will pay off first and how much of your debt you’ll pay off each month—and your timeline for paying them off. This will help motivate you to achieve debt freedom.
Applying Your Refund To High Interest Debt
If you have multiple debts with different interest rates, it may make sense to focus on paying off the debt with the highest interest rate first. This will save you money in the long run as you’ll be paying less interest over time. Additionally, it may help to improve your credit score, as paying off high-interest debt is typically viewed positively by credit agencies.
Alternatively, if you are feeling like you will never get out from underneath your debt, you may want to pay off the smallest balance so you feel a sense of accomplishment and that it is possible.
Talk To Someone Knowledgeable
Struggling with debt can be a daunting and overwhelming task, especially without the right resources and guidance. Talking to a reputable debt relief company, such as Progressive Debt Relief, is an effective way to get help in managing debt and figuring out a debt repayment plan that works for you. Debt relief professionals understand the ins and outs of debt management, so they can help provide advice on choosing appropriate debt reduction strategies for different types of debt. With their expertise, they can help simplify the debt relief process by letting you focus on what’s important—disciplined finance management skills to improve your financial future.
Final Thoughts
Overall, using your tax refund to pay off debt can be a great financial move. You can pay yourself back with the interest you are saving and free up money in your monthly budget, as well as potentially boosting your credit score. Ultimately, making use of your tax return responsibly is key to successful financial planning. If you’re struggling with debt and don’t know where to turn, contact Progressive Debt Relief. They offer debt relief services and customized strategies which could help strengthen your overall personal finances and achieve freedom from debt.
*This content must be used for informational purposes only. Progressive Debt Relief does not provide legal, financial or tax advice and the above should not be construed as such.
Are you overwhelmed by debt? Tired of that nagging feeling every time the bills arrive in the mail? Does it seem like bankruptcy may be the only way out? Before you begin going down the road of bankruptcy, take a moment to consider if there are other options available to get yourself back on track. While bankruptcy is one path for dealing with overwhelming debt, there may be more viable and cost-effective solutions depending on your situation. In this blog post, we’ll explore different possibilities so you can make an informed decision about pursuing bankruptcy or looking into alternative strategies to manage your debt and pay off your creditors once and for all.
What is bankruptcy?
Bankruptcy is often thought of as the end of the road. It is a legal process that many individuals and businesses use to recover from overwhelming debt. Bankruptcy offers a way out by providing relief from creditors through restructuring and/or discharging any outstanding debts that can’t be paid in full. By setting up a repayment plan, individuals in bankruptcy can make regular payments that suit their financial capabilities, with the goal of eventually being released from their debt burden.
There are several different types: chapter 7 bankruptcy involves the liquidation of assets; chapter 13 involves a repayment plan which allows individuals to keep their property; and chapter 11, intended for businesses and organizations with large debts, sets up restructuring agreements between creditors and debtors alike.
While bankruptcy can discharge certain types of debts, such as credit card debt and medical bills, there are limits to what bankruptcy will cover. Some not covered include:
· Alimony and child support
· Student loans
· Most taxes
· Criminal restitution payments and DUI fines
Other debts include mortgage payoffs and car loan payments if the bankruptcy filer does not wish to surrender the asset, personal loans from family members or friends, and civil court judgments in some cases. These are just some of the debts that bankruptcy will not cover and that must be paid off in full. Bankruptcy can be a powerful tool for getting out from underneath multiple forms of crippling debt, however it’s important to understand which debts it can forgive – and which it cannot by seeking legal advice.
The negative consequences of filing for bankruptcy
The truth is, bankruptcy can be a scary, intimidating process and does not always offer immediate benefits. Although filing for bankruptcy may give you access to a more manageable debt situation and stop some harassing collection efforts, there are several potential negatives and consequences you should consider before taking the big step.
8 possibly negative consequences of filing for bankruptcy
1.You may lose some of your possessions.
When you file for bankruptcy, you may have to give up some of your possessions in order to pay off your debts. This may include items such as your car, your home, or other valuable belongings.
2.Your credit score may be impacted.
Filing for bankruptcy can negatively impact your credit score. This can make it difficult to get a loan in the future, or even to rent an apartment or home. Unfortunately, depending on the type of bankruptcy being filed and other contributing circumstances, such as any prior court action taken against an individual, it could remain on a credit report for up to 10 years. During this time, it will also make obtaining loans more difficult – not impossible – unless you can demonstrate that you’ve worked hard to responsibly pay off any outstanding debt or amicably agreed with creditors in filing for bankruptcy.
3.You may have to pay higher interest rates in the future.
Another consequence of filing for bankruptcy is that you may have to pay higher interest rates on loans in the future. This is because lenders will view you as a higher risk borrower.
4.The bankruptcy process can be lengthy and expensive.
In order to file for bankruptcy, you must first complete a credit counseling course. You will also need to pay a filing fee, which is typically around $300. Additionally, it is recommended to hire an attorney to help you through the process, which can cost several thousand dollars. Upon initial filing for bankruptcy, there is an Adjustment of Debts Fee for Chapter 13 and Chapter 7. You may also be required to take credit counseling as well as debtor education classes. While it can be costly, it ultimately depends on your circumstances.
5.Bankruptcy can be stressful and emotional.
The bankruptcy process can be stressful and emotional. It can be difficult to deal with creditors and debt collectors while you are trying to file for bankruptcy. Additionally, you may feel you have failed financially.
6.You might lose your car.
It depends on several factors such as ownership status (if you lease or own), type of bankruptcy being filed, the value of your vehicle.
7. It may impact future employment
It is an unfortunate reality that having a bankruptcy on record can make it more challenging to secure employment; however, it does not mean impossible. Employers understand that life circumstances can cause financial insecurity, so bringing up your past credit history in an honest, straightforward way might help to assuage any misconceptions your potential employer may have. Additionally, while there are certain positions which are highly dependent upon credit ratings (such as banking jobs), there are many employers who view bankruptcy as a brief obstacle and not something that defines who you are or what sort of employee you will be.
8. Information contained in bankruptcy is a matter of public record
Information can be accessed by anyone who knows how to look for it and where. There are sometimes ways to limit what information is made public, but that depends on the type of bankruptcy being filed.
Factors to consider before filing for bankruptcy.
It’s a common misconception that bankruptcy wipes out all of your debts and takes your financial burden completely off your back. In reality it isn’t quite so simple. Bankruptcy may discharge some of your debts, but not all. You can also still owe money on mortgages, rent arrears, or maintenance payments after filing for bankruptcy. So while a bankruptcy declaration might be the light at the end of the tunnel you’ve been looking for, it certainly isn’t a straight-forward way to forget about bills forever.
Is bankruptcy the only answer to mounting debt problems?
There are alternatives to bankruptcy that may better suit your individual circumstances. Some options can help manage debt without the need to file bankruptcy, such as negotiating with creditors or obtaining debt relief. You can connect with professionals who can help manage your money. Talking to a financial advisor can provide guidance on how to manage outstanding debts, handling overdue payments, and setting up an emergency fund for when times are tough.
Additionally, establishing a budget can help you plan and monitor your spending and keep close tabs on your expenses. Having a budget also allows you to save more effectively, and helps you prioritize where to allocate your money instead of spending carelessly. Online budgeting tools and apps can provide relief by tracking spending and allowing you to create a payment plan. Above all else, budgeting imposes discipline which could be the difference between financial success and bankruptcy.
Other options to explore include credit counseling, debt consolidation, and debt settlement.
Credit counseling
Working with a credit counselor to develop a plan to repay your debts can be highly advantageous. A professional credit counselor will work with you to develop a plan for repaying your debt. This can be beneficial as it can help you to better understand your financial situation and develop a plan that fits your unique needs. Additionally, credit counseling can help you to improve your credit score over time. While credit counseling can be beneficial, it is important to choose a reputable credit counseling agency. Otherwise, you may end up paying more for the service than you would if you negotiated with your creditors on your own.
Debt consolidation
Debt consolidation can be a powerful tool in simplifying your debt and reducing interest charges. Rather than juggling multiple accounts, you’ll make one monthly payment to cover all existing debts. This could help pay off your debts faster and improve your credit score by reducing the number of open accounts on file with your creditors. However, it’s important to carefully evaluate how consolidating will affect both short-term and long-term financial goals, as well as consider any potential risks before diving into this option – failure to abide by repayment terms or defaulting may result in incurring even more debt.
Debt settlement
This process involves negotiating with your creditors in order to pay off what is owed for less than its full amount. You can choose between handling this yourself, which can be extremely stressful and time consuming or seeking out expert help from a specialized company, such as Progressive Debt Relief, who will have a wealth of experience in negotiating settlements with creditors.
Debt settlement could prove very rewarding depending on how far one’s creditors are willing to go. Perhaps more importantly, debt settlement offers another avenue towards financial freedom from extensive debts.
Final thoughts
Making the decision to file for bankruptcy is a difficult one. There are many factors to consider, and it’s important to understand all your options before moving forward. While bankruptcy may be the best option for some, there are alternatives that might better suit your individual circumstances. Connecting with a professional can help provide guidance on what steps to take next. If you are concerned with unsecured debt, Progressive Debt Relief offers free consultations so you can explore all your options and make the best decision for your unique situation. Give us a call today 1.877.590.1847– we’re here to help.
*This content must be used for informational purposes only. Progressive Debt Relief does not provide legal, financial or tax advice and the above should not be construed as such.
If you don’t have health insurance, or if your insurance doesn’t cover prescriptions, you can get a prescription discount card. These cards are offered by pharmaceutical companies, and they can give you discounts of up to 80% on brand-name drugs.
2. Shop around for the best prices
Prices for prescription drugs vary widely from pharmacy to pharmacy. It’s worth shopping around to find the best price. You can use websites like GoodRx or Blink Health to compare prices at different pharmacies. The cost of medicines can vary widely from one pharmacy to another, so it is important to shop around before filling a prescription. You can also check online pharmacies, as they often offer lower prices than brick-and-mortar pharmacies.
3. Use generic drugs whenever possible
Generic drugs are just as effective as brand-name drugs, but they cost much less. So, if your doctor prescribes a brand-name drug, ask if there’s a generic version that you could take instead. Generic medicines can be just as effective as brand-name medicines, but they typically cost much less. Ask your doctor or pharmacist if there is a generic version of the medicine you need and whether it would be appropriate for you to use it.
4. Get free or low-cost medicine from patient assistance programs
Many pharmaceutical companies offer programs that provide free or low-cost medicine to people who can’t afford it. To find out if you qualify for one of these programs, contact the pharmaceutical company that makes the drug you need.
5. Ask your doctor for samples
If you can’t afford the medication your doctor has prescribed, ask if he or she has any samples of the drug that you could take until you can afford to buy it.
6. Get a Good Health Insurance Plan
The first step to saving money on medicine is to get a good health insurance plan. There are a variety of health insurance plans available, and it is important to choose one that covers the medicines you need at a price you can afford. If you are unsure of which health insurance plan to choose, you can consult with a healthcare professional or an insurance broker.
7. Look for Discounts
There are a number of ways to get discounts on medicine, such as using coupons or shopping at discount stores. You can also ask your doctor or pharmacist about patient assistance programs, which provide free or low-cost medicines to those who qualify.
8. Get a Good Health Insurance Plan
The first step to saving money on medicine is to get a good health insurance plan. There are a variety of health insurance plans available, so it’s important to shop around and find one that meets your needs. A good health insurance plan will cover the cost of most, if not all, of your medical expenses.
9. Use Discount Programs
Many pharmacies offer discount programs that can help you save money on your prescriptions. For example, CVS offers a program called ExtraCare that gives discounts on certain drugs, and Walgreens has a program called Prescription Savings Club that offers discounts on both brand-name and generic drugs. Be sure to ask your pharmacist about any discount programs they offer.
10. Know Your Rights
Finally, it’s important to know your rights when it comes to prescription drugs. Many people assume that they need to pay for their medicine out of pocket, but this is not always the case. Some health insurance plans cover the cost of prescription drugs, and there are also government programs that can help with the cost of medicine. Under the Affordable Care Act, most health insurance plans must cover at least some prescription drugs. And under the new “Right to Try” law, patients with life-threatening illnesses can access experimental treatments that have not yet been approved by the FDA.
Final thoughts
There are a number of ways that you can cut costs on prescription drugs, and it may take some creativity and effort to find the best solution for your needs. However, the savings can be significant, so it is worth investigating prescriptions medicines thoroughly.
If you find yourself with credit or debit card debt or other types of unsecured debt such as cell phone, installment/payday loans, contact Progressive Debt Relief for a free consultation 1.877.590.1847 to explore ways to save money on your debt.
*This content must be used for informational purposes only. Progressive Debt Relief does not provide legal, financial or tax advice and the above should not be construed as such.
Debt is an intimidating thing to have. It’s easy to get overwhelmed and not know where to turn for help. But don’t despair – there are plenty of resources available, including debt relief books that can guide you through everything from budgeting basics to advanced strategies for tackling your debt head-on. From best-selling books written by top financial experts, to easy-to-read self-help manuals – there’s something out there for everyone looking for debt relief! In this blog post, we’ll look at some popular books that offer valuable insights on managing your debt that may help you get back to financially sound footing.
Jean Chatzky’s “Money Rules”
Jean Chatzky is a personal finance expert and author of multiple books about debt relief, including her best-selling book “Money Rules”. Curated with advice from dozens of experts, Chatzky’s book offers financial insight for debtors. She offers sound advice on minimizing debt and developing valuable techniques for budgeting and investing. Furthermore, she emphasizes the importance of making wise decisions with money from an early age, providing rich discussions and practical tips that appeal to readers of all ages. Jean Chatzky’s ‘Money Rules’ is for those looking to manage debt and make smart choices with their money.
“Pay It Down! From Debt to Wealth on $10 a Day” by Jean Chatzky
Many debt-ridden Americans have felt the sting of struggling with debt and are desperate for debt relief. Enter “Pay It Down! From Debt to Wealth on $10 a Day” by Jean Chatzky. This financial lifesaver provides debtors with a clear step-by-step path to becoming debt free, providing hope and debt relief in a straightforward approach. The action plan focuses on increasing income through smart debt management, so that debtors can meet their immediate needs as well as their debt obligations. With clear, easy-to-follow instructions and helpful support tools, this book provides readers with practical advice that can turn debt into wealth over time.
“How to Get Out of Debt, Stay Out of Debt, and Live Prosperously*: *Based on the Proven Principles and Techniques of Debtors Anonymous” by Jerrold Mundis
Based on the debt reduction strategies outlined in Debtors Anonymous by Jerrold Mundis, debt is manageable and preventable with some lifestyle changes and thoughtful spending choices. Mundis’ debt-relief guide is full of practical steps to help individuals address debt and create an action plan that suits their financial situation. By following his empowering tips, debtors can get out of debt, stay out of debt, and live in prosperity—so they don’t have to go through the struggle alone.
“The Debt Relief Manual: How to Get Out of Debt, Stay Out of Debt, and Live Prosperously” by Brette McWhorter Sember
This is an essential book for those ready to tackle debt. It is full of helpful suggestions, tips, and advice on debt relief specifically targeted at the individual or family level. With the tools gained from this debt relief guidebook, individuals can learn about debt reduction and management options for their particular situation in order to make progress toward becoming debt-free. Whether you’re looking to get out of debt quickly or make your debt more manageable over time, this book provides all you need to know about debt relief without becoming overwhelmed by too much financial knowledge.
“The Road Out of Debt: Bankruptcy and Other Solutions to Your Money Problems” by Jayne A. Myerson
Jayne A. Myerson’s book, “The Road Out of Debt: Bankruptcy and Other Solutions to Your Money Problems”, can help debt-laden individuals gain debt relief. Myerson provides valuable guidance regarding debt negotiation and debt management strategies and covers the consequences of both bankruptcy and debt consolidation. She also offers practical advice on how to budget sensibly, tips for improving one’s debt payments and working with creditors, as well as advice on how to rebuild good credit after becoming debt-free. Myerson helps anyone in debt break free from debt’s clutches with her comprehensive guide to debt relief solutions.
“Getting Out of Debt: Real-World Solutions for Your Money Problems from People Who Have Squared Up with Their Debts” by Gerri Detweiler
Whether you’re overwhelmed by debt or simply looking to develop better personal finance habits, “Getting Out of Debt: Real-World Solutions for Your Money Problems from People Who Have Squared Up with Their Debts” by Gerri Detweiler provides debt relief strategies that readers have indicated work. In addition to actionable advice, this book features debt success stories from real people who have experienced debt first-hand and offer inspiring words of how they were able to manage their debt. Above all, this book is a practical guide on how to face debt head-on and make the best decisions according to your financial situation. It is filled with wisdom that can help you take your finances into your own hands and start living debt free.
“The New York Times Complete Guide to Personal Finance: Revised and Updated” by Jason Zweig
Revised and updated by Jason Zweig, “The New York Times Complete Guide to Personal Finance” has helped many people find debt relief. This guide breaks down personal finance topics for the everyday person, making complex topics easier to understand. It outlines everything a reader needs to know in order to gain financial knowledge, from spending wisely, to paying debt responsibly. The book also provides guidance on setting goals and investing properly in order to build wealth and create financial stability. It uses a cool mix of anecdotes, graphs, charts, tables, and real-life stories of people who have been successful with debt relief and investing techniques, so readers can clearly see the hard-won success that comes from understanding debt relief strategies and other financial advice offered by the book.
Final thoughts
Managing your debt can be difficult and it is important to find the right resources to help you on your journey. The seven best-selling debt relief books presented here can offer guidance and support. These books provide actionable steps that can help you take control of your debt and improve your financial future. If you need assistance managing your debt, contact Progressive Debt Relief 877.590.1847 for a free consultation. Our team of experts can help you create a personalized plan to get out of debt and achieve financial freedom.
*This content is for informational purposes only and is not an endorsement of any of the books presented. Progressive Debt Relief does not receive any compensation from any of the books presented here. Progressive Debt Relief does not provide legal, financial or tax advice and the above should not be construed as such.
Deciding whether to use a debit or credit card can be tricky. On one hand, debit cards are convenient because they are linked directly to your bank account. This means that you can’t spend more money than you have. On the other hand, credit cards offer certain protections that debit cards don’t such as extended warranties on purchases and fraud protection. So, which should you use?
Are you constantly debating when to use your debit card and when to use your credit card? You’re not alone. In fact, there are a lot of factors to consider when it comes to using plastic.
Debit cards and credit cards differ in a few key ways. Let’s take a closer look at the pros and cons of both debit and credit cards.
How does a debit card work?
A debit card is a plastic card that gives the cardholder a set amount of funds against each purchase they make. Debit cards can be used for a variety of purposes, including:
-To make purchases: When you use a debit card to make a purchase, the funds are transferred from your account to the merchant’s account immediately. This type of transaction is known as a point-of-sale (POS) transaction.
-To withdraw cash: You can use your debit card to withdraw cash from an ATM. The funds will be deducted from your account immediately.
-To pay bills: You can use your debit card to pay bills online or over the phone. The funds will be deducted from your account immediately.
As you can see, debit cards can be very convenient. However, you should only use them when you have the funds available in your account to cover the transaction. Otherwise, you may be charged overdraft fees.
When does using a debit card make sense?
Debit cards are a great way to access your money without having to carry around cash or write checks. However, there are some situations where it’s better to use debit cards and others where it’s better to use another form of payment. For example, if you’re worried about identity theft, it’s best to use a debit card at a restaurant or brick and mortar store instead of giving your credit card number to a stranger.
Debit cards are also a good choice for making small purchases or for when you don’t have enough cash on hand. However, you might not want to use a debit card for large purchases or for travel because if your card is lost or stolen, you may not have access to your money right away.
How are debit cards different from credit cards?
Debit cards are different from credit cards in that they do not allow the cardholder to borrow money against the purchase. Instead, the cardholder can only spend the funds that they have in their account. This makes debit cards a safer option than credit cards against getting into trouble with debt, as there is no risk of falling into debt.
Debit cards also offer a number of other benefits, including convenience, security, and rewards. For example, most debit cards allow the cardholder to make purchases online, over the phone, or in person without having to carry around cash or checks. In addition, debit cards are usually linked to a secure online banking account, so cardholders can track their spending and ensure that their account balance remains healthy.
Finally, many debit cards offer rewards programs, such as cash back or points for every purchase made. These rewards can be used to offset future travel expenses or to simply save money on everyday purchases. Overall, debit cards offer a number of advantages over other payment methods, making them an ideal choice for those who are looking for a safe and convenient way to pay for their purchases.
When to avoid using a debit card
In general, it’s not a good idea to put big-ticket items – like furniture or electronics – on a debit card since they can be hard to track and may not qualify for fraud protection like credit cards do. Stick with credit cards when making these types of purchases so you can easily dispute any problems that arise later on down the road.
For online purchases, credit cards transactions are generally easier to dispute and minimize the chances of fraud. With debit cards, there is always a risk of your entire bank account being emptied in a fraudulent transaction.
It’s best to avoid using a debit card when staying at a hotel because your card is linked to your bank account and the hotel will often put a deposit hold for time that you’re staying, plus some extra money in case you have other incidental charges.
Auto rental companies also place a hold on money in your account while using a debit card, so you will not have access to those funds for the term of the vehicle rental.
When to consider using a credit card
In general, credit cards are best used for larger purchases that you can pay off over time. As long as you’re mindful of your spending and make payments on time, using a credit card can be a convenient way to manage your finances.
Here are some instances when using a credit card might make more sense than using a debit card:
– You’re making a big purchase that you can’t afford to pay off right away, but can pay off in a few weeks.
– You’re planning a trip and need to book hotels or flights.
– You’re renting a car.
– You’re shopping online.
– You need to make an emergency purchase.
Advantages of using a credit card
Using a credit card can offer several advantages over using cash or a debit card. For one thing, credit cards can help you build your credit history. By making timely payments and keeping your balances low, you can improve your creditworthiness and potentially qualify for more credit in the future.
This is important if you ever want to take out a loan for a major purchase, such as a house or car. Additionally, credit cards usually offer some form of consumer protection on purchases or fraud protection. This can give you peace of mind in case something goes wrong with a purchase.
Credit cards are also a good option if you’re trying to take advantage of credit card rewards, like cash back or points. The cash back or points for your purchases can be better with a credit card than what a debit card may offer. Just be sure to pay off your balance in full every month to avoid interest charges. And as previously mentioned.
Credit cards also offer protection against fraud. If your credit card is ever stolen or used without your permission, you can typically dispute the charges and get your money back.
When to avoid using a credit card
Of course, there are also times when it’s best to avoid using a credit card. For example, if you’re already struggling with debt, racking up more credit card debt will not help your financial situation. Additionally, if you know you won’t be able to pay off your credit card balance in full at the end of the month, it’s probably best to avoid using the credit card so you don’t end up paying interest on your purchases. And if you’re trying to save money, it can be very easy to make impulse buying decisions when you have a credit card handy.
Conclusion
So, which is better—debit or credit? The answer, as with most things in life, is that it depends. It depends on your spending habits, your goals, and your financial situation. If you tend to overspend or carry a balance from month-to-month, a debit card might be a better option for you. But if you’re looking to build your credit score or take advantage of rewards programs, a credit card might be the way to go.
Ultimately, whether you should use a debit or credit card depends on your individual financial situation. One thing is certain – it’s always best to stick to a budget.
If you find yourself in over your head with credit or debit card debt or other types of unsecured debt such as cell phone, installment/payday loans, contact Progressive Debt Relief for a free consultation. They have a wealth of experience and expertise working with major creditors. 1.877.590.1847.
*This content must be used for informational purposes only. Progressive Debt Relief does not provide legal, financial or tax advice and the above should not be construed as such.
The holidays are just around the corner, which means it’s time to start thinking about holiday shopping. For many people, the holiday season is a stressful time of year, due to the pressure of finding the perfect gifts for loved ones. However, it doesn’t have to be this way. With a little planning and forethought, holiday shopping can be stress free.
Here are a few tips to get you started:
Start by making a list of everyone you need to buy a gift for
Holiday shopping can be a daunting task, especially if you have a long list of people to buy for. However, there are a few strategies that can help you get through it without breaking the bank. First, start by making a list of everyone you need to buy a gift for. This will help you keep track of who you’ve already bought for and who you still need to shop for. Second, try to think of creative and personal gifts that will mean more to the recipient than something expensive. Third, take advantage of sales, coupons, and gift card specials to get the best deals on holiday gifts.
Break the list down into categories, such as family, friends, co-workers, etc.
If you have a long list of people to shop for, one way to make the task more manageable is to break the list down into categories. For example, you might have a separate list for family, friends, co-workers, etc. This will help you to focus your shopping and ensure that you don’t forget anyone. Another tip is to start early and spread out your shopping over a few weeks. This will help to relieve some of the holiday stress and allow you more time to enjoy the season.
Brainstorm gift ideas for each person on your list
To get started, sit down with a pen and paper, and make a list of everyone you need to buy for. Then, brainstorm gift ideas for each person. For example, if you’re buying for a family member who loves to cook, consider a new cookbook or kitchen gadget. If you’re buying for a friend who is always traveling, consider a new piece of luggage or a travel-themed gift. And if you’re buying for someone who is difficult to shop for, think about what they are interested in or what they might need. Once you have a few ideas, you can start narrowing down your options and making your holiday shopping list.
Set a budget for each category and stick to it
One way to make holiday shopping less stressful is to set a budget for each category and stick to it. This will help you stay on track and avoid overspending. To start, make a list of all the people you need to buy gifts for and what you would like to spend on each person.
Give gifts that won’t break the bank. There’s no need to spend a lot of money on gifts. Sometimes the best gifts are those that come from the heart, not the wallet. Make sure you have the money available and be sure to keep track of your spending, so you don’t go over budget and avoid going into debt.
Shop online and in-store sales to get the best deals
At times, holiday shopping can be a nightmare. You fight your way through crowds of people, only to find that the item you were looking for is sold out. And then there are the holiday sales: a seemingly never-ending barrage of emails and ads, each promising bigger and better deals. It can be tough to know where to find the best deals. However, there are a few general principles that can help you save money.
First, start early. By beginning your holiday shopping early, you’ll have more time to compare prices and find the best deals.
Second, take advantage of online and in-store sales. Many retailers offer holiday sales both online and, in their stores, so be sure to check both options before making a purchase. If the item your seeking is out of stock, see if it is available either online or in-store.
Finally, don’t be afraid to haggle. If you see an item that’s priced higher than you know it is advertised for elsewhere, try asking the salesperson if they’ll honor the lower price.
Wrap all your gifts once they’re bought so you don’t have to worry about it later
With people rushing to buy gifts, it can be difficult to find the time to wrap all of the presents. However, taking the time to wrap your gifts as soon as you buy them can save you a lot of stress later on. Not only will your gifts be ready to go when the holiday arrives, but you’ll also be less likely to forget about them and have to scramble at the last minute.
How to save money on holiday shopping
The holiday season is a time for giving, but it can also be a time for going broke. If you’re not careful, holiday shopping can quickly become a budget-buster. But there are ways to keep your spending in check and still make your loved ones feel special.
Shop early. Avoid the holiday rush by starting your shopping early. You’ll not only avoid the crowds, but you’ll also be more likely to find better deals. Compare prices and don’t just buy the first thing you see. Take the time to compare prices at different stores before making a purchase. Take advantage of sales. Many stores offer holiday sales, so be sure to take advantage of them. But beware of impulse buying just because something is on sale. Only buy items that you were planning to purchase anyway.
Final thoughts
Holiday shopping does not have to be a budget buster that leads to credit card debt, which can take months or years to climb out of. By following these tips, you can be ready and make the holiday shopping season a breeze.
Progressive Debt Relief specializes in resolving unsecured debt. If you need assistance with your unsecured debt, call Progressive Debt Relief, 877.590.1847 or schedule a free consultation online.
*This content must be used for informational purposes only. Progressive Debt Relief does not provide legal, financial or tax advice and the above should not be construed as such.
Money scams are unfortunately all too common. You may be thinking how can anyone fall for them? However, American consumers reported losing more than $5.8 billion to fraud last year, up from $3.4 billion in 2020 (an increase of more than 70%), according to the Federal Trade Commission. Almost 2.8 million consumers filed a fraud report to the agency in 2021 — the highest number on record dating back to 2001, according to the FTC.
Here are six of the most deceptive money scams to look out for. Be sure to protect yourself against these scams by being aware of them and knowing how to spot them. If you think you may have been scammed, report it to the authorities immediately.
The Royal Prince (Advance Fee) email scam
You’ve probably seen the emails before. They usually start with a sob story about how a wealthy prince or member of a royal family needs help moving millions of dollars out of the country. In exchange for your help, the prince promises to give you a percentage of the money. If you’ve ever wondered why anyone would fall for something like this, you’re not alone. Hundreds of people are scammed out of thousands of dollars every year by these so-called princes. So, how does the scam work? And why do people keep falling for it? Keep reading to find out.
The scammer will send an email to their target pretending to be a wealthy Royal prince or member of a royal family. In the email, they will explain that they need help moving millions of dollars out of their country. They will promise to give the recipient a percentage of the money in exchange for their help. The recipient is then instructed to wire money to cover “expenses” related to the transfer. Once the money is sent, it’s simply gone; there’s no way to track it or get it back.
In some cases, the scammer may try to string their victim along by asking for more and more money as new “expenses” arise. They may even go so far as to send fake documents purporting to be from banks or lawyers in an attempt to make the scam seem more legitimate.
Why People Fall for It
While it may seem impossible that anyone could fall for something like this, hundreds of people do every year. There are a few factors that contribute to this. First, many people simply don’t know that this type of thing happens. They think that if it were possible to scam someone out of millions of dollars, they would have heard about it before. Second, scammers are getting increasingly sophisticated in their methods and are becoming better at creating fake documents and websites that look legitimate. Finally, many people believe that they will be able to outsmart the scammer. They think that they’ll be able to figure out a way to get the money without actually sending any themselves. Unfortunately, by the time they realize that they’ve been scammed, it’s often too late.
Phishing scams
How to Spot Phishing Scams
Phishing scams are becoming more and more sophisticated, but there are still some telltale signs that can help you spot them. Here are some tips on how to protect yourself from becoming a victim of phishing.
What is phishing?
Phishing is a type of online identity theft that occurs when someone tries to trick you into disclosing personal information, such as your username, password, or credit card number. Phishers typically do this by sending an email or instant message that appears to be from a legitimate source, such as a bank or online retailer. They may even create a fake website that looks identical to the real thing. When you enter your personal information on the phony site or reply to the message, they now have access to your accounts and can use your information to commit fraud.
How can you protect yourself from phishing attacks?
The best defense against phishing is awareness. Be suspicious of any email or instant message that asks for personal information, even if it appears to be from a trusted source. If you’re not sure whether an email is legitimate, don’t click on any links in the message. Instead, go directly to the website in question and log in from there. And never enter personal information on a website that isn’t encrypted; look for https:// in the address bar before entering any sensitive data.
Phishing scams are becoming increasingly sophisticated, but there are still some ways to spot them. By being aware of the signs of phishing and taking steps to protect your personal information, you can avoid becoming a victim of identity theft.
Lottery scams
How to Spot a Lottery Scam
You’ve probably seen the emails or Facebook messages. They typically go something like this: “Congratulations! You have been selected to receive a free grant of $10,000! All you have to do is send us your bank account information and we will wire the money directly to you.” If you’re like most people, you probably just delete these messages without giving them a second thought. However, there are far too many people who actually get stung by this scam.
The lottery scam typically includes the following.
1. The message is unsolicited.
If you didn’t enter a lottery or contest, then you shouldn’t be getting an email or message telling you that you’ve won. Scammers will often try to create a sense of urgency by telling you that you need to act quickly to claim your prize. Don’t fall for it!
2. The message is from an unknown sender.
If the email or message is from someone you don’t know, it’s probably a scam. Even if the sender seems legitimate at first glance, be sure to do some additional research before responding. A simple Google search can often reveal whether someone is who they say they are.
3. The message contains grammatical errors.
These types of emails and even phishing emails often contain grammatical errors and strange phrasing. If you see errors in the message, it’s a good bet that it’s a scam.
4. You’re asked to pay upfront fees.
No legitimate organization will ever ask you to pay upfront fees to claim a prize. If you’re asked to pay taxes, shipping fees, or any other type of fee, it’s almost certainly a scam.
5. The offer seems too good to be true.
If it seems too good to be true, it probably is! Be especially wary of any offer that requires very little effort on your part but promises a large financial reward. These offers are almost always scams designed to steal your money.
Lottery scams are becoming increasingly common as scammers look for new ways to steal people’s hard-earned money. By following the tips in this blog post, you can easily spot a lottery scam and avoid becoming a victim. Remember, if an offer seems too good to be true, it probably is! When in doubt, err on the side of caution and don’t respond.
Credit card fraud
How to Spot Credit Card Fraud
There are a few ways to spot credit card fraud. First, you should regularly check your credit card statements for any unauthorized charges. If you see a charge from a merchant you don’t recognize, that’s a red flag that your card may have been compromised. You should also be on the lookout for any charges that are larger than usual. Sometimes, criminals will make small test charges on a stolen credit card before making a large purchase. So, if you see a charge that’s out of character, it’s worth investigating.
Another way to spot credit card fraud is to pay attention to your credit score. If you suddenly see a drop in your score, that could be an indication that someone has taken out new lines of credit in your name. You can also sign up for alerts from your credit card company so that you’re notified whenever there’s activity on your account. That way, you can catch any fraudulent charges as soon as they happen.
How to Avoid Credit Card Fraud
Credit card fraud is becoming increasingly common as more and more people shop online and use their credit cards for everyday purchases. But there are steps you can take to avoid becoming a victim of this type of crime.
The best way to avoid credit card fraud is by being vigilant about keeping your information safe. That means never sharing your PIN or full account number with anyone, not even family or friends. It also means being careful about where you use your credit card. Try to avoid using it at businesses that don’t appear to be reputable or secure. When shopping online, always make sure the website is encrypted before entering your payment information. You can tell if a website is encrypted if the URL starts with “https” rather than just “http.”
You should also keep an eye on your physical credit card. Never let it out of your sight when you’re making a purchase and be sure to keep track of it at all times. It’s also a good idea to monitor your account activity frequently so that you can catch any suspicious charges right away. By regularly checking your statements, monitoring your credit score, and being careful about where you use your card, you can help protect yourself from credit card fraudsters.
Tax refund scams
How to Avoid Tax Refund Scams
Hoping to get a big refund check from the IRS this year? However, before you start daydreaming about what you’ll do with that extra cash, beware of tax refund scams. Every year, thousands of people fall victim to scams where crooks pose as tax preparers or IRS officials to steal your hard-earned money. But there are a few simple steps you can take to protect yourself and avoid becoming a victim:
1. Don’t believe promises of unrealistic refunds. If it sounds too good to be true, it probably is. A reputable tax preparer will never guarantee a specific refund amount before reviewing your situation.
2. Be on the lookout for red flags. This includes things like a preparer who refuses to sign your return or gives you a blank return to sign, demands payment in cash only, or asks you to sign a blank Form W-2.
3. Don’t give out your personal information unless you’re sure who you’re dealing with. Be especially careful of email phishing scams where criminals pose as legitimate businesses or organizations to get your personal information. Never click on links or download attachments from unknown senders. And remember, the IRS will never initiate contact with you via email, text message, or social media.
4. Know what services you’re paying for. Make sure you understand exactly what services a tax preparer is offering and what their fee includes before signing any agreements.
5. Review your return carefully before signing it and ask questions about anything you don’t understand. You are ultimately responsible for the accuracy of your return, even if it’s prepared by someone else, so make sure everything looks correct before signing it and submitting it to the IRS.
When in doubt, consult with a tax professional or the IRS directly to ensure that you’re getting the most accurate information possible.
Check washing schemes
What is check washing?
Check washing is a type of fraud where criminals steal your checks, wash out the payee information, and write in their own name and amount. They can then cash the check at your bank or deposit it into their own account. And since the check appears to be legitimate, there’s not much you can do to get your money back.
How can I protect myself from check washing schemes?
There are several things you can do to protect yourself from check washing schemes:
1. Keep track of your checks: Be sure to keep track of all the checks you write. This way, if one of your checks is stolen and washed, you’ll know right away and can act accordingly.
2. Use a pen with indelible ink: When you write a check, be sure to use a pen with indelible ink so that it can’t be easily altered. If someone tries to change the payee information on your check, it will be obvious that the check has been tampered with.
3. Safeguard your checks: Don’t leave your checks lying around where they can easily be stolen. Keep them in a safe place where only you have access to them.
4. Review your statements: Be sure to review your bank statements carefully each month. If you see any suspicious activity, report it to your bank immediately.
Final thoughts
By following the tips above, you can help protect yourself from becoming a victim of these financial schemes. Remember, if you think something might be too good to be true, it probably is. Trust your gut and always err on the side of caution when it comes to giving out personal information or writing checks.
Progressive Debt Relief has extensive experience resolving unsecured debt. If you need assistance with your unsecured debt, call Progressive Debt Relief, 877.590.1847 or schedule a free consultation online.
*This content must be used for informational purposes only. Progressive Debt Relief does not provide legal, financial or tax advice and the above should not be construed as such.
If you attended college, you probably have some form of student loan debt. According to The Institute for College Access & Success, 70% of college seniors who graduated in 2014 had student loan debt, with an average of $28,950 per borrower. As if that weren’t bad enough, the interest rates on those loans are often high, and there’s no guarantee that you’ll be able to find a job that will allow you to pay them off. However, there are some student loan debt forgiveness programs available if you qualify.
The different types of student loan debt forgiveness and discharge programs available
You’ve graduated from college and are ready to start your career. There’s just one problem: you’re buried under a mountain of student loan debt. As you start to make your student loan payments, you may be wondering if there’s any way to get your loans forgiven. The good news is that there are several different types of student loan forgiveness programs available. The bad news is that they can be very difficult to qualify for.
The first type of student loan forgiveness program is the Public Service Loan Forgiveness Program. This program is available to government employees and nonprofit workers. To qualify, you must make 120 on-time monthly payments. If you work full-time for a qualifying employer, the remaining balance on your loans will be forgiven after 10 years of payments.
The second type is the Teacher Loan Forgiveness Program. This program is available to teachers who teach full-time in certain high-needs fields for at least five years. If you qualify, up to $17,500 of your loans may be forgiven.
The third type of student loan forgiveness program is the Perkins Loan Cancellation and Discharge program. This program is available to teachers, law enforcement officers, volunteers in certain organizations, and members of the military. If you qualify, 100% of your Perkins Loans may be forgiven after five years of qualifying service.
Finally, there are a few Student Loan Discharge Programs available to those who qualify. These programs include the following: Closed School Discharge, Borrower Defense to Repayment Discharge, Total and Permanent Disability Discharge, Total and Permanent Disability for Veterans, and Discharge Due to Death (Parents PLUS Loans). These programs are varied and have different criteria for approval. But many online resources exist for these programs should you wish to research these programs more fully.
How to apply for student loan debt forgiveness
If you think you might qualify for student loan forgiveness, the first step is to contact your lender and see what options are available to you. They may have information on student loan forgiveness programs that you didn’t know about. Once you’ve found a program that you think you qualify for, the next step is to fill out an application and submit it to your lender. If everything goes well, you could be on your way to becoming debt-free!
What to do if you’re denied student loan debt forgiveness
Denied student loan debt forgiveness? Don’t worry, you’re not alone. In fact, according to a recent study, nearly 70% of all student loan borrowers are denied student loan debt forgiveness each year. But don’t despair – there are still options available to you. First, you can appeal the decision. Contact the financial aid office at your school and request a review of your file. Be sure to have all of your documentation in place before you make the call, as this will help to speed up the process. If you’re still not satisfied with the outcome, you can also consider consolidating your student loans or enrolling in an income-driven repayment plan.
Can You Settle Your Student Loans?
According to Forbes magazine, “student loan debt settlement is an option for borrowers who are struggling to repay their loans and are unable to qualify for income-driven repayment or public service loan forgiveness.”
Income-driven repayment plans lower your monthly payments by basing them on your income and family size. Public service loan forgiveness cancels your remaining student loan balance if you work for a qualifying employer full-time for 10 years while making 120 on-time monthly payments.
If you do not qualify for either of these programs, you may still be able to settle your student loans. The process of settling student loans is similar to that of other types of debt; however, there are a few key differences to keep in mind.
For one thing, private lenders are more likely to settle than federal lenders. This is because private lenders do not have as many options for collecting money from borrowers who default on their loans. Private lenders also tend to be more flexible when it comes to negotiating settlements.
Another key difference is that settled student loans are treated as taxable income by the IRS. This means that if you settle your $10,000 student loan for $5,000, you will have to pay taxes on the $5,000 as if it were regular income.
The best way to avoid this is to negotiate a lump sum payment with the lender rather than making monthly payments over time. That way, you will only have to pay taxes on the lump sum when you file your taxes for that year rather than paying taxes plus interest on the entire original loan amount every month.
Tips for paying off your student loans faster
If you’re one of the millions of Americans struggling to pay off student loan debt, you’re not alone. The average student loan borrower owes over $37,000, and the total student loan debt in the U.S. has reached nearly $1.6 trillion. While it can feel overwhelming, there are some things you can do to pay off your student loans faster.
One option is to consolidate your loans into a single payment. This can help you save money on interest and make it easier to keep track of your payments. Another option is to sign up for auto-debit, which will automatically deduct your monthly payment from your account. This can help you avoid missed payments and late fees. You may also want to consider making extra payments when you can afford it. Even an extra $50 per month can make a big difference over time.
Whatever strategy you choose, remember that there’s no magic solution for paying off student loans. It will take time and effort, but if you’re diligent, you can get rid of that debt for good.
If you find yourself overwhelmed with student loan debt or other types of unsecured debt such as cell phone, or installment/payday loans, contact Progressive Debt Relief for a free consultation. They have a wealth of experience and expertise working with major creditors. 1.877.590.1847.
*This content must be used for informational purposes only. Progressive Debt Relief does not provide legal, financial or tax advice and the above should not be construed as such.
Crypto currency is a digital or virtual asset that uses cryptography for security. Crypto currencies are decentralized, meaning they are not subject to government or financial institution control. Bitcoin, the first and most well-known crypto currency, was created in 2009. Crypto currencies are created through a process called “mining.” Miners confirm transactions and add them to the crypto currency’s blockchain, which is a publicly visible ledger. In return for their work, miners are rewarded with crypto currency. Because crypto currencies are not regulated by governments or financial institutions, they have become popular with people who want to keep their transactions private. However, crypto currencies are also subject to volatility, as their prices can fluctuate quickly and rapidly. As a result, crypto currencies are not suitable for everyone.
How to buy crypto currency
Cryptocurrency is a digital or virtual currency that uses cryptography for security. Bitcoin, the best-known crypto currency, was created in 2009. Blockchain, the technology crypto currencies are built on, is a distributed ledger system that is secure, and transparent.
Crypto currencies are bought and sold on crypto exchanges. To buy crypto currency, you first need to set up an account on a crypto exchange. Once you have set up your account and verified your identity, you will be able to deposit fiat currency, for example, USD, (US dollars), into your account. Once you have deposited fiat currency, you can use it to buy crypto currency. Some of the most popular crypto currencies are Bitcoin, Ethereum and Litecoin. Coinbase is one of the largest and most popular crypto exchanges for buying crypto currency with fiat currency. However, there are many other different crypto exchanges available, so it is important to do your research to find one that is reputable and offers the coins that you want to buy.
Once you have bought crypto currency, it is stored in a digital wallet. A digital wallet is like a bank account for crypto currency. It allows you to store, send and receive crypto currency. You can store your digital wallet on your computer or mobile device, or you can use a service like Coinbase which offers a hosted digital wallet. When you want to spend your crypto currency, you send it from your digital wallet to the recipient’s digital wallet.
The benefits of using crypto currency as money
The crypto currency revolution has been building momentum for years, and it’s showing no signs of slowing down. Crypto currencies offer a number of advantages over traditional fiat currencies, including increased security, anonymity, and decentralization. They are also substantially more efficient than fiat currencies, thanks to the blockchain technology that powers them, and they are quickly becoming the preferred choice of payment for people all over the world.
The risks of using crypto currency as money
As crypto currencies have become more popular, some people are beginning to use them as a form of money. However, there are a number of risks associated with using them. First, crypto currencies are not backed by any government or Central bank. This means that their value can fluctuate wildly, making them unreliable. Secondly, crypto currencies are often used to buy illegal goods and services on the black market, since the buyers and seller are anonymous. The ability to remain anonymous also means if you are not able to access your digital wallet or it is hacked, that you can lose your crypto currency. Finally, crypto currencies are not regulated by any financial authority. This means that there is no guarantee that you will be able to get your money back if something goes wrong. For these reasons, it is important to be aware of the risks before using crypto currency as money.
How to store and protect your crypto currency
Although it is digital asset, it is a real asset, and it needs to be treated as such. Here are some tips on how to store and protect your crypto currency.
First, you need to understand the concept of the blockchain. The blockchain is a distributed database that stores information about all crypto currency transactions. It is the backbone of crypto currency, and it is what allows crypto currencies to be secure and decentralized. Every time a transaction is made, it is recorded on the blockchain. This way, there is a permanent record of all crypto currency transactions, although again, the identities for those making the transactions remains anonymous.
Second, you need to choose a wallet that supports crypto currency. There are many different types of wallets available, so make sure to do your research before choosing one. A good wallet will offer security features such as multifactor authentication and keeping your private keys (a type of special password) offline (known as “cold storage”).
Finally, remember that crypto currency is still a new and developing asset class. As such, it is subject to extreme volatility. If you’re not comfortable with the risks, then you may want to reconsider using them. In either case it is wise to start out with a small amount of money. But if you’re willing to take on the risk, then crypto currency can offer convenience and potential growth rewards.
The future of crypto currency
Crypto enthusiasts believe that crypto currency is here to stay. In the past few years, we’ve seen a surge in the popularity of crypto currency, and it shows no signs of slowing down. With the rise of blockchain technology, crypto currency has become a viable alternative to traditional currency. And while there are still some skeptics out there, more and more people are beginning to see the potential of crypto currency.
So, what does the future hold for crypto currency? Well, it’s hard to say for sure. But one thing is certain: crypto currency is here to stay. With its convenience, security, and anonymity, crypto currency is quickly becoming a popular choice for those looking for an alternative to traditional money. So, whatever the future holds, one thing is for sure: crypto currency is here to stay.
Crypto currency is often seen as the Wild West of investments. And, to some extent, that’s true. The crypto currency market is notoriously volatile, and scams are not uncommon. But crypto currency is also an incredibly powerful tool that is only going to become more important in the years to come. The key to understanding crypto currency is understanding blockchain, the technology that underlies it. Blockchain is a decentralized, secure database that can be used to store any kind of information. Crypto currency is simply one application of blockchain. And while crypto currency may be risky, investing in it now could pay off big in the future. So, if you’re feeling brave, the future of crypto currency might just be worth exploring.
Is crypto currency the future of money? It seems to be headed in that direction and it certainty has a lot of potential. Although it is still a new and an emerging technology with a lot of risks, it could very well play a role in our financial landscape moving forward. As this technology and its uses evolve, it’s likely that we will see even more widespread use of it as a medium of exchange.
The value of crypto currencies can be very volatile and has been known to go up and down very quickly. Before buying or investing in crypto currency, it is important to do your research, talk to your financial advisor, and understand the risks involved.
If you have unsecured debt, such as credit card, cell phone, or installment/payday loans, contact Progressive Debt Relief for a free consultation. They have a wealth of experience and expertise working with major creditors. 1.877.590.1847.
*This content must be used for informational purposes only. Progressive Debt Relief does not provide legal, financial or tax advice and the above should not be construed as such.
Are you constantly feeling like your paycheck isn’t stretching as far as it used to? You’re not alone. Inflation has been gradually eroding the value of our money, and it may be a while before it slows down. So, what can you do to fight back? Here are a few tips for beating inflation and keeping your finances strong despite rising prices.
Start by creating a budget and sticking to it
If you’re like most people, you probably think that budgets are restrictive and boring. But if you want to beat inflation, you need to start by creating a budget and sticking to it. Here are a few tips to help you get started:
1. Figure out what your regular expenses are and track them over time. This will help you to identify areas where you can cut back.
2. When it comes to big-ticket items like vacations or new cars, remember that it’s important to save up in advance. Trying to finance these items with credit can be a recipe for disaster.
3. Make sure to account for unexpected expenses in your budget. This could include things like medical bills or car repairs. By setting aside money each month, you’ll be prepared for anything that comes your way.
4. Finally, don’t be afraid to give yourself some wiggle room in your budget. If you’re too restrictive, you’ll quickly become discouraged and are more likely to abandon your budget altogether. Try to strike a balance between being realistic and being too rigid.
Shop around for the best deals on groceries, clothing, and other household items
In today’s economy, it’s more important than ever to be a savvy shopper. With the cost of living on the rise, it’s essential to find ways to stretch your budget. One way to do this is to shop around for the best deals on groceries, clothing, and other household items. By taking the time to compare prices, you can save money on your monthly expenses. Here are a few tips to help you beat inflation:
– Plan your shopping trips in advance. Make a list of what you need and compare prices at different stores before you buy.
– Take advantage of sales and coupons. If you see an item on sale, stock up! You can also save money by using coupons when you shop.
– Buy in bulk. Buying larger quantities can help you save money in the long run. If you have the space, consider stockpiling non-perishable items like toilet paper and paper towels.
Stay informed about current events and economic conditions so you can make informed decisions about your finances
Staying informed about current events and economic conditions is essential if you want to make smart decisions with your money. After all, knowing what’s going on in the world can help you anticipate changes in the marketplace and adjust your budget accordingly. Here are a few tips for staying on top of current events and economic conditions:
-Read the business section of your local newspaper. This is a great way to stay up to date on local companies and industries that may be affected by changes in the economy.
-Check out online business news sources. Sites like Bloomberg and The Wall Street Journal offer comprehensive coverage of national and international business news.
-Talk to your financial advisor. Your advisor should be able to give you insights into how current events and economic conditions could impact your finances.
-Stay up to date on government policies. Changes in government policy can have a big impact on the economy, so it’s important to stay informed about what’s going on in Washington.
Cut back on unnecessary expenses, like cable TV or eating out at restaurants
If you’re looking for ways to save money, you may want to consider trimming some of your expenses. Cable TV and dining out at restaurants are two common areas where people tend to spend too much.
Here are a few tips for cutting back on these expenses:
Cable TV: When it comes to cable TV, you don’t need to go completely without – there are plenty of ways to watch your favorite shows without breaking the bank. One option is to downsize your package, or ditch cable entirely and opt for a cheaper streaming service like Netflix or Hulu. You can also take advantage of free trials and special promotions to save money on your cable bill.
Restaurants: Eating out at restaurants can be expensive, but it doesn’t have to be. If you’re trying to save money, stick to restaurants that offer affordable lunch specials or happy hour menus. You can also split entrees with a friend or order appetizers instead of full meals. And when it comes to drinks, water is free!
Buy in bulk when possible, to take advantage of lower prices
Anyone who has stepped into a grocery store in the past year knows that the cost of living is on the rise. In fact, inflation has been climbing steadily for several years, and there is no end in sight. One way to combat the rising cost of living is to take advantage of discounts by buying in bulk. Many stores offer significant discounts on bulk purchases, and these savings can add up over time. In addition, look for coupons from product manufacturers and the stores you’re buying from.
Put money aside each month into a savings account or investment fund
Many people find that their savings dwindle over time, despite their best efforts. The problem is that the cost of living steadily rises, while incomes remain stagnant. This phenomenon is known as inflation, and it can have a major impact on your ability to save money. There are a few tips that can help you beat inflation and keep your savings intact. First, try to put away a fixed percentage of your income each month, rather than a fixed dollar amount. This way, as your salary goes up, so will your savings. Second, invest in assets that tend to appreciate over time, such as stocks or real estate. These investments will grow along with the cost of living, allowing you to maintain your purchasing power. Finally, don’t forget to review your savings goals on a regular basis and adjust them accordingly. By following these tips, you can make sure that your hard-earned savings don’t disappear into thin air.
It can be difficult to keep up with inflation, however there are ways to hedge against it and protect your hard-earned money. Stay informed on the economy, be savvy when making purchases, review your expenses and make changes where possible.
Having credit card and payday loan debt during inflation can be hazardous. Interest rates have been going up, which means your debt is costing more. If you need assistance with your unsecured debt, call Progressive Debt Relief, 877.590.1847 or schedule a free consultation online.
*This content must be used for informational purposes only. Progressive Debt Relief does not provide legal, financial or tax advice and the above should not be construed as such.
We all know the internet can be a dangerous place. Any information you share online is at risk of being stolen, used, or simply published without your consent. Your name, identity, and reputation can be damaged if you’re not careful. In this blog post, we’ll discuss some tips for keeping yourself safe online and protecting your personal information.
Don’t share too much personal information online
It’s no secret that the internet can be a minefield of personal information. Just a few clicks can reveal your addresses, phone numbers, email addresses, and even your credit card number.
So how can you protect yourself from identity theft and other online threats? The best defense is to be aware of what you’re sharing and with whom you’re sharing it. For example, think twice before posting your home address or phone number on a social networking site.
It’s important to stop and think about how much personal information you’re comfortable sharing online. Remember, once something is posted online, it can be very difficult to take back.
And when filling out online forms, be sure you are on a reputable site and read the privacy policy to see how your information will be used. By being careful about what you share online, you can help to keep your personal information safe from online criminals.
Use strong passwords and change them often
One of the best ways to protect your online information is to use strong passwords and to change them regularly. This can help safeguard your online information and help keep your identity safe. A strong password is at least eight characters long and includes a mix of uppercase and lowercase letters, numbers, and symbols. It should be something that would be difficult for someone else to guess. When creating a new password, avoid using easily accessible personal information like your birthdate or your pet’s name. And once you’ve created a strong password, don’t reuse it on multiple sites. If one account is compromised, all of your other accounts are at risk.
Be aware of what you’re clicking on – scam emails and websites are everywhere
These days, it seems like we are being bombarded by scams. Phishing emails promise free vacations or warn of dire consequences if you don’t click on a link. Suspicious websites try to entice you with too-good-to-be-true deals. It can be tough to know what’s real and what’s not, but there are a few things you can do to protect yourself. First, be wary of any email or website that asks you for personal information or financial data. Legitimate companies will never ask for your password or social security number via email. Secondly, take a close look at the URL of any website you’re considering clicking on – if it looks fishy, it probably is. Finally, remember that if something seems too good to be true, it probably is. By being aware of these common scams, you can protect yourself from becoming a victim.
Set your social media privacy settings to “private”
Most people are aware that they should be careful about what they post on social media. However, many people don’t realize that their privacy settings may not be as secure as they think. By default, most social media platforms have public settings, which means that anyone can see your posts, photos, and personal information. If you’re not careful, it’s easy to unwittingly share too much information with the world. That’s why it’s important to consider setting your social media privacy settings to “private.” When your account is private, only people who you approve can see your posts and access your personal information. This can help to protect you from identity theft, harassment, and other unwanted attention. So, if you’re not already using private settings on your social media accounts, be sure to strongly consider changing your settings today.
Check your credit report regularly for any unauthorized activity
One of the best ways to protect your financial health is to keep an eye on your credit report. By law, you are entitled to a free credit report from each of the three major credit reporting agencies every twelve months. This is a valuable tool for monitoring your credit health, as it can help you spot any unauthorized activity. When reviewing your credit report, be sure to check all of the personal information for accuracy. This includes your name, address, date of birth, and Social Security number. You should also check all of the account information to ensure that there are no errors. If you find any discrepancies, be sure to dispute them with the appropriate agency. By regularly checking your credit report, you can help to safeguard your financial future.
Install anti-virus software on all your devices
It’s more important than ever to protect your devices from viruses. That’s why you should make sure to install anti-virus software on all your devices, including your computer, phone, and tablet. Anti-virus software helps to identify and remove malicious software, keeping your devices safe from harm. There are many different types of anti-virus software available, so it’s important to choose one that’s right for your needs. Some factors to consider include the type of devices you have, the amount of protection you need, and the level of customer support offered.
Choose a program that regularly releases updates to stay ahead of new viruses. You should be able to easily install and set up the program with minimal tech knowledge. Of course, you’ll want to choose a program that actually works! Read reviews from other users to get an idea of the programs’ effectiveness.
In the online world it seems like anything goes, so it’s more important than ever to protect your name and reputation. Fortunately, by following some simple guidelines there are ways to do this without breaking the bank.
If you need a good debt relief company to help you with your unsecured debt, look no further and contact Progressive Debt Relief. We’ve been in business for almost 20 years, have extensive experience and expertise working with major creditors, numerous excellent reviews, IAPDA accreditation, no upfront fees, and no minimums to qualify! Call 877.590.1847 or schedule a free consultation online today.
*This content must be used for informational purposes only. Progressive Debt Relief does not provide legal, financial or tax advice and the above should not be construed as such.
Cookie Consent
We use essential cookies to make our site work. With your consent, we may also use non-essential cookies to improve user experience and analyze website traffic. We use cookies to help us collect and use information about your interactions with our website. By clicking "Accept All," you agree to our website's cookie use as described in our Privacy Policy. You can decline non-essential cookies by clicking "Reject All." You can change your non-essential cookie settings at any time by clicking "Preferences."
Cookie Preferences
Manage your cookie preferences below:
Essential cookies enable basic functions and are necessary for the proper function of the website.
Name
Description
Duration
sdui_panel_minimized
Stores a temporary preference indicating whether a user interface panel or toolbar has been collapsed/minimized to save screen space.
Session
sdui_panel_open
Stores a temporary preference indicating whether a specific admin panel or inspector drawer is currently expanded/open in the site's back-end interface.
Session
Cookie Preferences
This cookie is used to store the user's cookie consent preferences.
30 days
_tccl_visitor
Stores a randomly generated visitor ID so GoDaddy's traffic tracking recognizes a returning visitor across sessions.
1 year
_tccl_visit
Stores a randomly generated ID for the current visit so page views and clicks can be grouped into one session.
30 minutes
CloudFlare provides web performance and security solutions, enhancing site speed and protecting against threats.
The cf_ob_info cookie provides information on: The HTTP Status Code returned by the origin web server. The Ray ID of the original failed request. The data center serving the traffic
session
__cflb
When enabling session affinity with Cloudflare Load Balancer, Cloudflare sets a __cflb cookie with a unique value on the first response to the requesting client. Cloudflare routes future requests to the same origin, optimizing network resource usage. In the event of a failover, Cloudflare sets a new __cflb cookie to direct future requests to the failover pool.
session
__cfseq
Sequence rules uses cookies to track the order of requests a user has made and the time between requests and makes them available via Cloudflare Rules. This allows you to write rules that match valid or invalid sequences. The specific cookies used to validate sequences are called sequence cookies.
session
cf_clearance
Whether a CAPTCHA or Javascript challenge has been solved.
session
_cfuvid
The _cfuvid cookie is only set when a site uses this option in a Rate Limiting Rule, and is only used to allow the Cloudflare WAF to distinguish individual users who share the same IP address.
session
__cf_bm
Cloudflare's bot products identify and mitigate automated traffic to protect your site from bad bots. Cloudflare places the __cf_bm cookie on End User devices that access Customer sites that are protected by Bot Management or Bot Fight Mode. The __cf_bm cookie is necessary for the proper functioning of these bot solutions.
session
__cfruid
Used by the content network, Cloudflare, to identify trusted web traffic.
session
cf_chl_rc_m
These cookies are for internal use which allows Cloudflare to identify production issues on clients.
session
cf_chl_rc_ni
These cookies are for internal use which allows Cloudflare to identify production issues on clients.
session
cf_chl_rc_i
These cookies are for internal use which allows Cloudflare to identify production issues on clients.
session
__cfwaitingroom
The __cfwaitingroom cookie is only used to track visitors that access a waiting room enabled host and path combination for a zone. Visitors using a browser that does not accept cookies cannot visit the host and path combination while the waiting room is active.
session
cf_use_ob
The cf_use_ob cookie informs Cloudflare to fetch the requested resource from the Always Online cache on the designated port. Applicable values are: 0, 80, and 443. The cf_ob_info and cf_use_ob cookies are persistent cookies that expire after 30 seconds.
session
These cookies are needed for adding comments on this website.
Name
Description
Duration
comment_author_url
Used to track the user across multiple sessions.
Session
comment_author
Used to track the user across multiple sessions.
Session
comment_author_email
Used to track the user across multiple sessions.
Session
Statistics cookies collect information anonymously. This information helps us understand how visitors use our website.