Progressive Debt Relief

Regain Control of your Finances


Author: progressivedebtrelief

  • 4 Fees to Be Aware of Before Applying for A New Credit Card

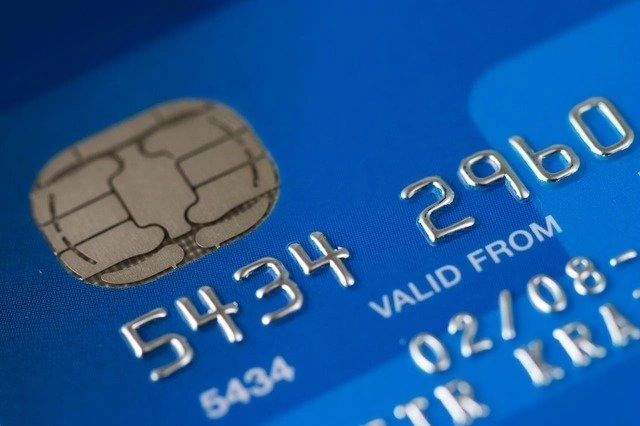
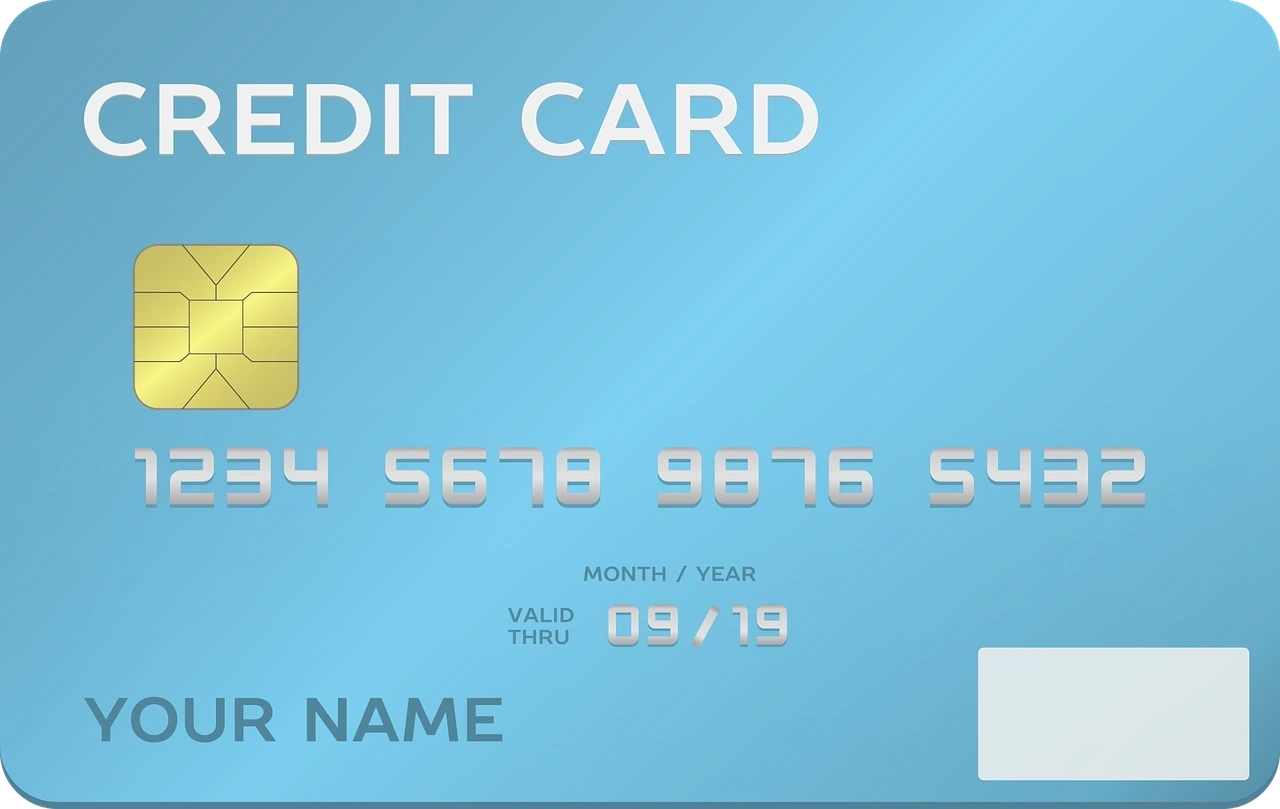
    A visual of a Credit Card that shows the front side parts of a credit card: Where the name is located, the card number, the validity date and the chip.

    Many credit card companies offer numerous benefits for signing up for a new credit card.  They often come with enticing card member benefits and rewards such as cash back, hotel and airline travel rewards, etc. However, you need to know how much the card can potentially cost you by checking out all the fees associated with the card before applying.

    1. Annual fee

    Many reward cards charge an annual fee just for having the cards. Fees can range from a nominal $50 to as high as $500 or more. Typically, higher the fee, the more generous the benefits. Do the calculations on how much you expect to spend with the card and the reward compensation you will receive for doing so to calculate and ensure a positive return on the annual fee. 

    Consider how often you’ll use the card to earn rewards and whether the membership perks are worthwhile before committing to a card that charges an annual fee.

    2. Interest charges

    It is critical to know the interest rate on the new card you are considering. Of course, you can avoid interest charges if you pay off your balance on time every month; however, if you cannot pay off your balance, the finance charges can be astronomical. You can never 100% predict when a life event may happen and leave you without being able to pay the balance off for that month. The cost of a high interest rate will typically squash the value of the reward benefits. On the other hand, if you have a decent amount of savings that you can tap in the event you need to pay off unexpected expenses, then the new card will probably make sense.  

    Credit card companies will often entice new applicants with a limited time 0% promotional rate, which can be a great if you need to carry a balance for a brief time while paying off some other debt. Be careful, if you are not sure you will have the money available to pay the balance in full when the promotional rate ends, you could get walloped with a lot of interest on the accumulated balance. If you are not sure, it might be best to pass on opening the new card.

    3. Late fees

    If you do not pay your bill on time, or you pay less than the minimum amount due, your credit card company will typically charge you a late fee. Late fees can range from $28 to $39, with the average late fee around $36, according to U.S. News research. If you are assessed a late fee, you can always call the customer service number on your statement and let them know this was a one-time mistake. Most credit card companies will grant a credit for the late fee if it was the first time you were late.  

    4. Foreign transaction fees

    A foreign transaction fee is a charge by your credit card company to use your card to make a purchase while in a foreign country. You should also ask if they have any foreign transaction fees, which are often around 3%. There are credit card companies that do not charge foreign currency fees. So if you plan to travel overseas and spend a lot on your card, it may make sense to obtain a card with no foreign currency fees.

    Also, if you plan to travel outside of the United States and plan to make purchases with your card while overseas you should contact your credit card company, so they know to authorize you to use your card while away. Otherwise, your purchase could be declined. 

    Consider the interest rate, the annual and late fees, and foreign transaction fees in deciding whether a new credit card is right for you. 

    If you have credit card debt or any other type of unsecured debt such as payday and installment loans, medical and phone bills, please call Progressive Debt Relief 1.877.590.1847 for a free consultation. 
  • Is buy now, pay later a good idea?

    A keyboard with the enter key replaced a visual that says: "Add to cart"

    Shopping online is so easy- in a matter of minutes you can find and purchase whatever you are looking for, and with buy now, pay later (BNPL) programs, it is even easier to make a purchase by postponing payments until later. 

    Buy now, pay later is not new, it is like the old-school layaway plans department stores used to offer, that let shoppers hold their purchases by making periodic installment payments, usually interest-free. The difference is with buy now, pay later plans, you receive the product up front and pay in incremental payments later. 

    Who’s behind the buy now, pay later trend? 

    Installment payments are gaining popularity due to the surge in online shopping and retailers are being creative in trying to capture more sales by making it easier to hit the buy button. Buy now, pay later options are beginning to be offered by online retailers like Target, Walmart, and Amazon, and many BNPL providers are also including browser extensions, which can be downloaded and let you apply for online purchases. There are also the apps, which let you use installment payment options. 

    BNPL providers such as Afterpay, Affirm, Klarna, Sezzle and Zip are leading the way and PayPal is starting its own product. Amazon and Apple are partnering with Affirm and Target is teaming-up with Sezzle. According to a recent survey by LendingTree, approximately one-third of shoppers have financed purchases with BNPL and among those buyers, nearly two-thirds have done so five or more times in the past.   

    Financing for big-ticket purchases like home gym equipment can make financial sense, especially when financing is offered 0%. What is new with buy now, pay later financing is that it is being offered on small ticket items. Target’s, Sezzle offering is testing out installment purchases for food and other everyday product purchases. Shoppers can now utilize these short-term loan offerings to buy just about anything.  

    Why pay now when you can pay later? 

    As buy now, pay later programs make it easier for people to press the buy button, it will inevitably lead to many consumers spending more than they can afford, which can result in consumer debt. Unlike credit card purchases, which let you repay in 30 days, BNPL loans often require repayment every two weeks. 

    What should buyers be aware of when using BNPL?

    If you are trying to build your credit score, most BNPL lenders do not report your on-time payments to the credit reporting companies, like credit card companies do, which means you may be losing out on the chance to build positive credit and boost your credit score. 

    According to LendingTree, 70% of the users of buy now, pay later programs have been charged interest or fees for missed payments. It can become difficult to keep track of multiple BNPL accounts which can lead to missed payments, late fees, deferred interest, or other penalties.

    If you find yourself having a difficult time with buy now, pay later debt or other unsecured debt, including medical bills, credit cards and payday, cash advance, and installment loans, you can contact Progressive Debt Relief at 877-590-1847 or by submitting a free consultation form. 

  • When to consider filing for bankruptcy?

    A photo of a woman's hand signing a paper.

    According to Bankrate’s 2019 Financial Security Index Poll, nearly three out of 10 Americans do not have enough emergency funds available to deal with a financial crisis. In the event of a financial crisis, the lack of an emergency fund usually leads to depending on unsecured debt, such as credit cards, installment and payday loans, to help fund daily expenses. When debts mount up to the point where the debtor sees no light at the end of the tunnel bankruptcy is often viewed as a last resort to solve a financial crisis.

    Bankruptcy is a legal process where a debtor, which can be an individual or entity, such as a business or municipality, declares bankruptcy to acquire relief from their debt. Bankruptcy is normally accomplished through a discharge of the debt or through a restructuring of the debt. You can file for bankruptcy on your own, or you can enlist a bankruptcy lawyer. 

    Although there is a stigma attached with filing for bankruptcy, it can happen to anyone. There are numerous reasons for filing for bankruptcy including, unemployment, overuse of credit, marital dissolutions, unexpected losses, and large medical expenses. 

    A study performed by Harvard University indicates that medical expenses are the number one cause of bankruptcy, accounting for 62% of all personal bankruptcies. Serious illnesses or injuries can easily result in hundreds of thousands of dollars in medical expenses, even with medical insurance, that can rapidly wipe out savings. 

    Unexpected losses such as the loss of property due to natural disasters such as hurricanes, tornadoes, earthquakes, floods, etc., for which the property owner is not insured or adequately insured, can lead some into bankruptcy. Beyond the loss of property comes the expense of finding a new place to live, replacing clothes and food. 

    Some people have a difficult time staying within their budget and find themselves spending beyond their means, which can lead to excessive credit card debt, installment and payday loans, as well as other personal loans. This becomes problematic when the borrower becomes overextended and is unable to make the minimum payment. 

    To help protect yourself from bankruptcy, it is vital to build up an emergency fund, always have adequate medical and property insurance coverage, and avoid the overuse of credit so that your debt-to-credit ratio remains low. If you are unsure, talk to a professional who can help determine if you have enough coverage and are financially prepared.

    If you find yourself struggling with unsecured debt, such as medical bills, payday and installment loans, you can always contact Progressive Debt Relief  and schedule a free consultation.

  • What are some options for bankruptcy vs debt relief?

    alt=""

    When you are in over your head with debt it can feel overwhelming, like a hole you cannot get out of. Unfortunately, there are many Americans drowning in debt. The Coronavirus pandemic has caused quite a few Americans to experience financial distress due to job losses or reduced incomes. This led to borrowing, and lots of it.  Slightly more than half of adults, 51% or roughly 51 million people, added to their credit card balances, according to a report by CreditCards.com.  44% blame the pandemic for their additional borrowing. 

    What are the options to getting out of debt? Some of the most utilized options for getting out of debt are bankruptcy, debt settlement, and debt management. 

    Bankruptcy

    Bankruptcy offers you the chance to start over again by forgiving debts that you simply cannot pay while giving creditors a chance to obtain some way of repayment based on the assets you have available for liquidation. Bankruptcy usually requires you to appear in court, and upon the successful completion of bankruptcy proceedings, you are relieved of the debt obligations you incurred prior to filing for bankruptcy. 

    While bankruptcy can appear to be an easy way to solve your debt troubles, it is important to remember, if you file under either Chapter 7 or Chapter 13 of the U.S. Bankruptcy Code, it will become public record.  Bankruptcy will be reported to the credit bureaus, which will severely lower your credit score. This is a result of your debts being reported to the credit bureaus as not paid in full and these notations can stay on your report for seven to ten years, depending on the specifics of your bankruptcy filing. They could affect your ability to obtain a loan in the future and even future employment for those applying for jobs that require dealing with money, such as bookkeeping, accounting, payroll, etc. Bankruptcy filings can have expensive court fees and attorneys’ fees, which may not be recoverable. 

    Debt Settlement 

    Debt settlement, (also known as debt reduction, debt negotiation or debt resolution) can also be an effective option for getting out of debt. Debt settlement is when a settlement is reached after negotiating with a debtor’s unsecured creditor. Typically, the creditor agrees to forgive a large part of the debt per the terms of the written agreement. It is common that the debtor makes one lump-sum payment or a schedule of monthly payments, in exchange for the creditor agreeing to consider the debt closed. If the debtor performs what is agreed in the negotiation, there should be no outstanding debt from the creditor on the debtor’s credit report.

    Debt Management

    Debt management is another way to reduce unsecured debt, such as credit cards and personal loans. Debt management typically uses financial planning and budgeting to reduce and take steps to eliminate debt.  You can do debt management on your own by creating a personalized budget that can outline your income and expenses and areas to pay off your debts.  Calculators and financial management apps are tools that can be helpful in managing your debt. You can also try negotiating with your creditors to gain favorable terms, such as removing any late fees incurred, structuring lower monthly payments or a lower interest rate.  It is best if you can make an immediate payment while on the phone with the creditor to show you are serious in paying back the debt. 

    The other option would be to engage a credit counseling service. Credit counselors can help you come up with a debt management plan to repay your debt and will work on your behalf to negotiate a payment plan with your creditors. The payment plan is structured to payoff and eliminate your debts. An advantage of using a credit counselor is that they usually have experience negotiating with creditors. 

    If you find yourself needing assistance with unsecured debt and are interested in exploring debt relief options, Progressive Debt Relief is available for free consultations. Call 877.590.1847 or use our contact form to schedule a complimentary consultation today.

  • How to Recognize Phishing Emails

    alt=""

    Phishing is a fraudulent tactic used by cyber criminals to try and obtain personal information such as passwords, credit card numbers, or to deploy malicious software on the victim’s computer.  One of the primary methods scammers use is email, where they appear to be from a known business or organization, but in reality, are fraudulent. 

    According to Alert Logic, nearly 1.5 million phishing sites are created each month and the typical user received an average of 16 phishing emails per month.

    How can you tell if the email you received is real? If you look closely at the sender’s email address you will notice a domain name after the @ sign. For example, if the email purports to be from Amazon, the address should have amazon.com somewhere after the @ sign in the email address. If it contains anything other than the business’ domain, you should delete it immediately. Fraudulent emails also often contain grammatical mistakes or misspellings.  

    Some Examples of Phishing

    One example of phishing is an email that informs you to update your username and password. Another example would be receiving an email asking you to enter login details (on a replica of the website you think you are visiting). Again, you want to look closely at the domain name and if it does not match leave immediately. You then want to run your anti-virus software and clear your cache and cookies through your browsers Settings, then Privacy and services. 

    Phishing attacks have become more sophisticated with some internet criminals creating mirror web sites that look like the real website. These fabricated sites allow the criminal to observe everything on the victim’s computer while they navigate the site.  According to the FBI, phishing was the most common type of cybercrime in 2020—and phishing incidents nearly doubled in frequency, from 114,702 incidents in 2019, to 241,324 incidents in 2020. If you suspect you have received a phishing email you can report it to the Federal Bureau of Investigations Internet Crime Complaint Center (IC3). 

    If you use Outlook, you can report suspicious emails to Microsoft by select the phishing email you want to report. Select Junk in the Outlook toolbar and choose Phishing in the drop-down menu. Select Report to send Microsoft a phishing email notice. The email will be automatically moved to your Junk Email folder. Google’s Gmail and other email platforms have similar capabilities. 

    According to internet security firm Tessian, 96% of phishing attacks are email based. The most impersonated brands include Microsoft, DHL, Linked In, Amazon, IKEA, Google, PayPal, Chase, and Rakuten. This is no surprise as most people have an account with at least one of these businesses. 

    According to Symantec’s 2019 Internet Security Threat Report (ISTR), the top five subject lines for business email compromise attacks included: 

    1. Urgent

    2. Request

    3. Important

    4. Payment

    5. Attention

    Remember to always keep your guard up when doing anything on the internet. Cyber-criminals are looking to capitalize on any vulnerabilities they can find. If you find yourself needing help with unsecured debt, such as payday and installment loans, credit card and medical debt, you can always call on Progressive Debt Relief. Free consultations are available by calling 877.590.1847 or using our contact form. 

  • Protecting Yourself Against Harmful Text Messages

    alt=""

    We’ve all received that strange text message alerting us to some vague information about an account we have that directs us to click on a hotlink. These links usually lead to trouble and are most often an attempt to steal your information, such as credit cards, user IDs, and passwords. These messages can even be an attempt to hack your phone by installing harmful malware that uncovers your personal information without you even knowing about it. 

    Cybersecurity researchers have revealed a critical and undetected vulnerability in SIM cards that could allow hackers to access a smartphone just by sending an SMS, “short message service,” which is used to send text messages between cellphones. Your cell device could be hacked as soon as you click on the malicious link given in the SMS.  

    You do not want to engage or text “STOP” with these unclear text messages unless you know the sender is legitimate. Cyber criminals can use your response as an indication you received your message and are now actively engaged in your messages, which can motivate them to send you more messages. Your information can also be sold to other cyber criminals who are looking for “verified active” phone numbers. If you are unsure of the text message, contact the company via a known phone number or website before clicking on the link. If it is a scam text simply delete it, turn your phone off and then turn it on again. 

    Cell phone hacking statistics are frightening

    According to RSA Security, around 60% of the world’s cyberattacks are initiated on mobile devices. Approximately 80% of attacks against mobile devices take place via apps. According to Symantec, third-party app stores hosted 99.9% of detected mobile malware, and are therefore the main cause of recent security breaches involving mobile devices. 

    What To Do About Spam Text Messages

    There are several things you can do to block unwanted text messages or stop them before they reach you. If you have an iPhone, Apple has detailed instructions on how block phone numbers, contacts, and emails on your iPhone, iPad, or iPod touch that can be found on Apple’s website support. For Android devices, you can visit Google’s website support page. 

    In addition to blocking spam text messages, you can report them by using the option to report junk or spam on your phone. You can also copy the message then forward it to 7726 (SPAM) as well as report it to the Federal Trade Commission at ReportFraud.ftc.gov. 

    If these steps are not enough you can purchase apps such as RoboKiller, which is available for iPhone and Android devices, and can dramatically reduce the spam you receive from both phone calls and text messages. RoboKiller has a 7-day free trial, and then there is a per month or per year subscription option.

    Progressive Debt Relief has the ability and experience to settle unsecured debt, and its purpose is to improve your quality of life by offering sound financial solutions to fit your individual needs. Free consultations are available by calling 877.590.1847 or through the online contact form.

  • The Importance of Maintaining a Good Credit Score

    alt=""

    Everyone wants a good credit score, it is the key to loan and credit card approval, higher loan amounts, and attractive interest rates. To achieve a good credit score, which according to Experian, one of the three major credit bureaus, is a score of 700 or above, you must be credit worthy. Your creditworthiness is a measure of how well you manage your debts. The credit bureaus, Experian, Equifax, and TransUnion are data collection agencies that gather your account information from various creditors and provide that information to a consumer reporting agency in the United States. Each credit bureau calculates your credit score based on an assessment of your credit history. 

    A credit score is based on the following five factors, according to Fair Isaac Corporation, a data analytics company focused on credit scoring services, and utilized by the credit bureaus.  

    1. 35% of your score is based on your payment history. This is an indicator of whether you make payments on time and how often you make payments. Payments over 30 days late will typically be reported by your lender and hurt your credit scores. The higher your proportion of on-time payments, the higher your credit score. Every time you miss a payment, you negatively impact your score.

    2. 30% of your credit score is based on outstanding loan balances and credit cards. This is based on the entire amount you owe, the number and types of credit you have, and the proportion of money owed compared to how much credit you have available. High balances and maxed-out credit cards will lower your credit score; however, if you pay smaller balances on time, it can raise it. 

    3. 15% of you score is based on the length of your credit history. The longer your history of making timely payments, the higher your score will be. Credit scoring models generally look at the average age of your credit when factoring in credit history. 

    4. 10% of your score is based on the types of credit accounts you have. Having a mix of secured and unsecured debt, including installment loans, home loans, and retail and credit cards might help improve your score. 

    5. The final 10% is made up of recent credit activity. If you opened a lot of accounts recently or applied to open accounts, it might suggest you are undergoing financial trouble and could lower your score. However, shopping for a loan is not considered risky and should not negatively impact your credit score.

    The best way to improve your credit score is to use loans and credit cards responsibly and make timely payments. The more your credit history shows that you are doing this over time, the more willing lenders will be to offer you credit at a competitive rate. 

    If you find yourself struggling with debt, including credit cards, installment, and payday loans, you can always contact the Progressive Debt Relief  account managers at 877.590.1847 or through our contact form.

  • What are the options for personal loans?

    alt=""

    There are numerous situations that arise when you need to borrow money. Fortunately, there are plenty of loan options available including unsecured personal loans which are popular because they can usually be funded in 48 hours or less, and you can use them for almost anything you want. The three major sources for unsecured personal loans include banks, credit unions and online lenders. If you need money quickly and do not want to place an asset as collateral, an unsecured personal loan can make a lot of sense.

    Typically, you will need a credit score in the mid-600s to qualify for most unsecured personal loans and a score of 740 or above to get the best rates. Unsecured personal loan interest rates can vary widely, with a typical range from 5% and 36%, depending on numerous factors, including credit history. Shop around for the best loan terms that meet your needs including loan amount, interest rate, repayment period and fees. 

    If you belong to a credit union check with them as an unsecured personal loan from a credit union can have several benefits over personal loans from other lenders. Credit union loans typically offer lower interest rates and fees. Also, a credit union can often be more open to lending to borrowers with less-than-perfect credit. 

    To join a credit union, you need to be a part of that credit union’s field of membership. That means you have a common bond with other members of the credit union such as your employer has established a relationship with a credit union, and all employees are allowed to join. Community-based credit unions allow anybody who lives in a certain community (a city, state, or another geographic region) to become a member.

    Payday loans are one of the easiest ways to get fast cash; however, be careful as the interest rates can be extremely high and the terms can force you into rolling over the loan for additional, less than favorable terms. Payday lenders are no longer required to check that a borrower can repay their loan when it comes due, therefore borrowers often get trapped into having to borrow again and again, at interest rates that can be as high as 400%. 

    If you find yourself needing assistance with unsecured loan debt, such as payday and installment loans, you can always contact Progressive Debt Relief for a free consultation with one of our account managers. You can either call 877.590.1847 or use our online contact form.

  • Steps You Can Take To Repair Your Credit

    alt=""

    Your credit score is a key indicator of your credit worthiness and will impact your ability to obtain loans as well as the interest rate you will be offered. If you find your credit score is low or has gone down since you last checked, there are steps you can take to improve it.

    Begin by requesting a copy of your credit report. Federal law provides you the right to receive a free copy of your credit report annually from the three national credit bureaus (Equifax, Experian, and TransUnion) at AnnualCreditReport.com. 

    After receiving your reports, thoroughly review them for any errors, such as outdated information, mistaken or merged accounts with similar names or addresses, and clerical errors that could be hurting your credit score.  If you detect an error on your credit report, you can dispute the error by writing the credit reporting company what you believe is wrong, why, and include copies of documents that support your dispute. Request that the information be removed or corrected and enclose the section of your credit report that contains the disputed information. You may want to send your letter by certified mail and request a return receipt, so that you will have a record that your letter was received.

    If your credit report is accurate and your credit score is below what is generally considered an average credit score, 620 to 679, you will need to repair your credit. One way to do this is to consistently make payments on time.  If you have a credit card it is imperative to show the credit bureaus that you have a history of paying on time.  Also, pay down as much of your outstanding balance as possible. Your credit score is partially based off the total amount of credit that you have.  

    If you do not have a credit card or cannot obtain a credit card, you could pursue a secured credit card which is like a regular credit card except it uses your bank account as collateral.  Theoretically, you can charge up to the amount in your bank account.  This will help rebuild your credit as you pay off your bill each month.  It shows that you are managing your credit responsibility.

    Remember it can take time to rebuild your credit, but it will be very worthwhile once you do. If you need assistance with outstanding debts, such as payday and installment loans, credit cards, and medical bills, you can turn to the account managers at Progressive Debt Relief for a free consultation by calling 877.590.1847 or through our online form. 

  • What is unsecured debt?

    alt=""

    Unsecured debt is a category of debt that does not require a pledge of assets. such as automobiles, stocks, house, etc. The asset or property with which you pledge to secure the loan is known as collateral. An unsecured loan is considered unsecured debt and is typically granted based on the amount of the loan, the borrower’s income, as well as credit history. A co-signer may be required, which means if you default on the loan the co-signer would be responsible for making the loan payments. Some unsecured debt lenders require automatic monthly payment deductions from your bank account as a condition of loan approval. It is important to carefully review the terms of the unsecured loan as it may come with a higher interest rate, late payment fees, as well as shorter payback. 

     Some examples of unsecured debt include. 

    • A credit card is a payment card that enables the cardholder to pay a merchant for goods and services based on the cardholder’s approved debt level. 

    • A medical bill includes debts owed to a hospital, private physician, health care clinic, treatment center, etc. 

    • A payday loan is a relatively small amount of money loaned at a high rate of interest with an agreement that it will be repaid when the borrower receives their next paycheck. 

    • A cash advance is a way of obtaining money immediately through a pledge to your credit card’s line of credit. 

    What happens if you do not pay an unsecured loan?

    If you do not make your loan payment on the due date you may be subject to late payment fees.  In the event you stop making payments for several months, you may be considered in default by the lender. Default is the failure to meet the legal obligations of a loan.

    Although unsecured debt creates less stress by not having your assets pledged to the lender, if you default on the loan, you will have consequences. For starters, your credit score will most likely be negatively impacted, as the creditor will report you to the main credit bureaus, Equifax, Experian, and Trans Union. Should you need a loan in the future, the potential creditor will most likely pull your credit history and find your default. In addition to reporting your default, the lender will may put your account into collections and take legal action against you to regain some or all of the outstanding debt owed. 

    If you have unsecured debt and it has become a problem, consider turning to the account managers at Progressive Debt Relief for a free consultation by either calling 877-590-1847 or through our online form.

  • Can I go to jail if I do not pay a payday loan?

    alt=""

    It is a horrible thought- jail time for not repaying a payday loan. Although threats of jail time are sometimes used by some less than scrupulous lenders, failure to repay a payday loan is not a criminal offense. If you are threatened with arrest for nonpayment, the Consumer Financial Protection Bureau advises contacting your state attorney general’s office. 

    Keep in mind, a payday loan is a binding, legal agreement, and depending on the state you live in, some payday lenders will use bad-check laws that can lead to bank overdraft fees, garnishment of paychecks, collection calls, and filing a criminal complaint that may result in having to appear in court. You should never ignore a court summons, even if the criminal complaint was filed mistakenly. Show up on time, be respectful of the court by answering the judge politely and request the lender provide proof that you owe the money. 

    If you fail to appear in court, the lender will usually win a default judgment, and the court can begin the process of collecting the money you owe. If you are unable to pay the judgment, the court may allow you to make installment payments that you can afford. However, depending on the state you live in, a judgment for the lender could result in property liens, bank account levies and garnishment of wages. 

    What if you cannot pay the payday loan?

    Before paying a payday loan be sure to focus on your necessities first, such as food, utility bills and paying rent. Check to see if you are eligible for community assistance, as there is often help with rent, utilities, or food. 

    How to get ahead of your payday loan debt 

    You can try to settle your pay day loan debt for less than you owe. Most lenders would rather collect money directly from you instead of selling your payday loan debt to a collection agency for pennies on the dollar. 

    Working with a debt relief company who specializes in settling payday loan debt, can be very advantageous. Debt relief firms typically have the expertise to negotiate with payday loan debt lenders and collection agencies. They also often have the experience to come to a resolution with the lender.   

    Whatever you do, take action so you can avoid the additional stress that payday loan debt causes.  One action you can take is to contact Progressive Debt Relief for a free consultation by calling 877.590.1847 or through the contact form. 

  • What to do if you have credit card debt?

    alt=""

    It is easy to see how credit card debt can become a problem. Credit cards are accepted virtually everywhere, and they are very convenient to use when making a purchase. With credit cards there is no need to fumble around your wallet or purse searching for dollars and coins. The problem is when you receive your credit card statement at the end of the month, and you do not have the funds to pay it off completely. It is funny how the amount owed always seems to be more than you remember charging. Unless you faithfully deduct each of your charges from your checking or savings account balance you may end up charging more than you can pay for. The result is often to make a payment that is less than the full statement balance. Of course, this incurs a carryover of what was not paid, to next the month billing cycle, and the dreaded interest charges begin to incur.  

    The best and fastest way to stop the credit card debt cycle is of course to not use your credit card. Try putting your credit card away and only use cash for purchases until your credit card is completely paid off. This strategy could prevent you from becoming swallowed up in debt while also helping you to spend less. Numerous studies have shown that consumers are willing to pay more for an item when they are using a credit card instead of cash. For most, swiping or entering the numbers from a credit card requires little thought compared to counting out cold, hard cash.  

    At first, it may feel a little uncomfortable and less convenient to only use cash; however, that is why this strategy can work well. It is more difficult to make cash purchases and consequently you should spend less. But what about online shopping? You could use PayPal, or other payment services such as Venmo, which deduct money directly from your checking or savings account.

    Do not make the mistake of using another credit card and thinking you will pay both credit cards off at the end of the 30-day card cycle. Using another credit card will most likely result in accumulating more debt by having another credit card balance you cannot pay off. This is how credit card debt can become a big problem. 

    If you do find yourself with multiple credit card balance’s you will have two basic options to pay them off. Either pay off the credit card with the highest interest rate first or the one with the lowest amount owed. To help you decide which option is best for you, think about whether you would rather save money on interest, or eliminate the entire credit card balance quickly. Which ever option you decide, be sure to stick with it until all your balances are paid off. 

    If credit card or other unsecured debt has become a problem, consider turning to the Progressive Debt Relief account management team. We offer free consultations by either calling 877-590-1847 or by submitting our online form. 

  • The importance of using a debt verification letter

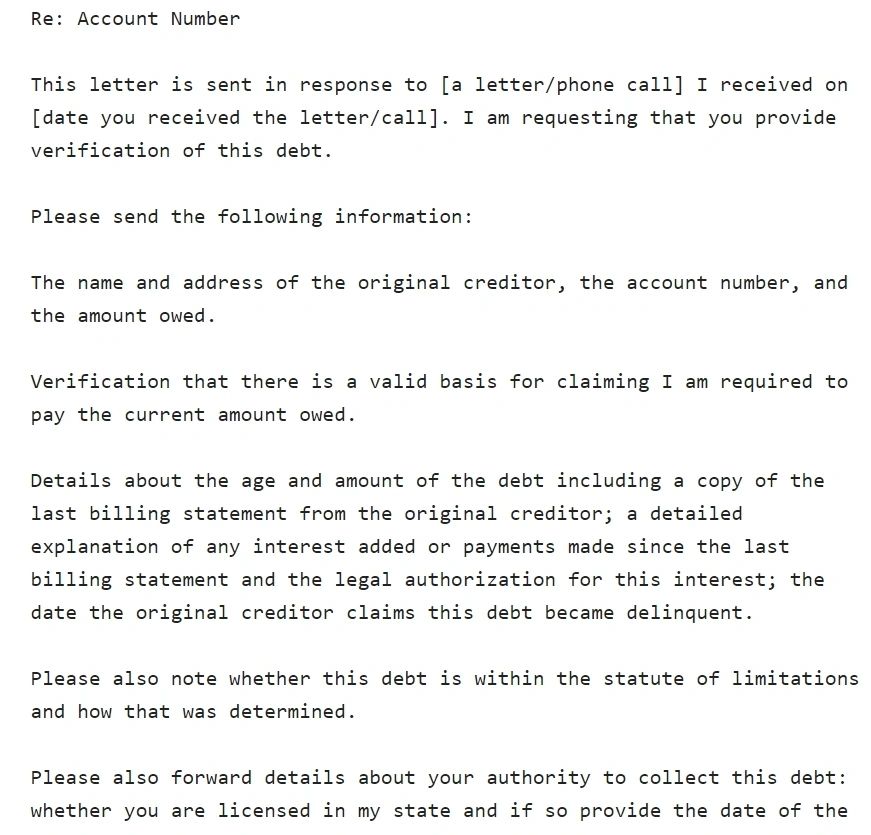
    Sample debt validation letter template requesting a collector to verify a debt by providing the original creditor's details, amount owed, copy of the last billing statement, interest calculations, statute of limitations status, and proof of license to collect.

    If you receive a call from a debt collector, before you discuss anything, be sure you have received a debt validation letter, which debt collectors are legally required to send you. The debt validation letter specifies the debt, how much you owe and other pertinent information. If you are not sure of the debt you are being asked to pay, or there is inaccurate information, you can send the debt collector a debt verification letter requesting additional information. You have the legal right to require the debt collector to prove you owe the money under the Fair Debt Collection Practices Act (FDCPA). 

    A debt verification letter can be a powerful tool for interacting with debt collectors. The key is to be thorough in your request for debt verification. Your letter should state that you dispute the validity of the debt and that you want documentation verifying the debt. Also, request the name and address of the original creditor. If you have made payments on the debt or have paid the debt off, include copies of documentation illustrating the payments you have made. If the debt collector fails to respond to your validation letter after 30 days, then legally they must cease collection efforts, and remove negative items placed by them on your credit report.

    Keep in mind, you only have 30 days to respond to a debt validation letter. If you do not dispute the debt specified in the letter within 30 days, the debt will be assumed to be valid, which means the debt collector can continue to contact you until it is paid. If the debt specified in the debt validation letter is legitimate and completely accurate then you are required to pay the debt in full. 

    If you receive calls from a collection agency, you can inform them you prefer to pay the original creditor and request they provide their address so you can send them a cease-and-desist letter. If they call you while at work, you can inform them your employer does not allow you to take the calls at work and to not call again. 

    Contact the original debtor and try negotiating a payment plan or a reduction of the total amount due. If you do reach a settlement, be prepared to make a payment, as most creditors will expect to receive a payment from you immediately. If the debt has been sold to a collection agency you can also try negotiating with them. Be sure to keep records of any payments you have made.  

    If you find yourself needing help with debt, call Progressive Debt Relief 877.590.1847 and talk to one of our account managers who are available Monday through Friday from 9:00-5:30 pm EST. You can also request a free consultation by submitting our online contact form.  

  • Tips for controlling spending and sticking with a budget

    alt=""

    It’s easy to spend money, not as easy to save. After all, you must spend money to live. Overspending, or spending outside of your budget however can become a bad habit. The trick to sticking with a budget is to constrain your spending to the things you must spend money on. Prioritize the essentials such as rent or mortgage, groceries, power bill, car loan, insurance, etc. 

    When shopping, have a specific purpose with a set list of items that are within your budget. Avoid any temptation to purchase items that do not fit within your budget. Print a copy of your budget and carry it with you to remind yourself of the commitment you have made to your financial goals. 

    Gaining control over your money requires awareness. Learn to recognize situations that place you in a difficult spending situation. For example, never shop while hungry at the grocery store, or shop at the mall or department store if you are depressed, as this can lead to binge shopping. Be aware of those times when you spent money that was outside of your budget. Create a journal where you can write down your thoughts and feelings as to why you spent erroneously. Your journal can become a tool you can rely on for help in understanding how to master your money. Avoid purchasing any non-budgeted items with a credit card. Small dollar purchases on credit cards are easy to make and can really add up.

    Once your spending is under control, and the necessities are paid, you can move any left-over money to a savings account for unknown expenses, which unfortunately will arise. Having an emergency fund will negate the need for payday loans, installment loans or credit card debt. All of which can carry high interest rates and thus can be difficult to pay off. This can set you back financially and potentially ruin your budget. Curtailing spending and sticking to your budget will be difficult at first, but over time you will develop the self-discipline required to achieve your financial goals.

    If you find yourself struggling with unsecured debt  such as pay day and installment loans or credit cards, cell phone bills, etc. you can always reach out to Progressive Debt Relief by calling 877.590.1847 or by submitting a contact form for a free consultation.

  • 7 Tips for Establishing Financial Wellness

    Financial wellness is an essential component to one’s overall well-being. Just as exercise and healthy eating are important components toward physical wellness, there are things one can do to achieve financial wellness.  

    1. Review your current financial situation. In order to get a firm grip on your financial situation you need to thoroughly review your finances. You must have a clear picture of the current state of your finances to carefully select goals that will improve your financial picture. This will require listing all your income and assets as well as bill payments and outstanding debts. You can then understand your net financial worth. 

    2. Establish financial goals and priorities. It all starts with having goals for your finances and setting priorities for those goals. It is important to write down your financial goals. Make sure they are realistic, and you believe you can accomplish them, otherwise they are wishes. For example, if your goal is to become debt free, write it down along with the reasons why you want to become debt free, and how it will feel to accomplish your goal. Having clear goals with an emotional attachment, along with the reasons it is important to accomplish your goal will help you achieve it. Include the steps you will take such as paying off a small credit card balance by a certain date.

    3. Create a budget. Once you have a good grasp of your finances you will need to create a monthly budget that lists your income and all your expenses for the month. At that point you can start to prioritize your goals and make any adjustments to your spending that will help you achieve your goals.

    4. Establish an emergency fund. Having money in the bank for when emergencies arise will provide you some peace of mind. There are times in life when unfortunate situations happen and having money you can quickly access will make these times easier to deal with and less burdensome. 

    5. Pay off debt. Having a clear understanding of all your debt will help you on your path to financial wellness. Debt such as payday loans, installment loans, and credit cards usually carry high interest rates. It is important to understand the interest rate for each debt and focus on paying off debt with the highest interest rate first. 

    6. Review your progress regularly. At least once a month you should review your financial goals and the progress you are making. If you are having a discouraging month and not accomplishing your goals, do not give up. Understand that setbacks are temporary, revaluate why you want to achieve your goal and continue to take the steps to achieve it. 

    7. Save for retirement. One day you will want to retire and no longer have to work. Social security only goes so far that is why it is important to contribute to your retirement account. Find out if your employer offers a 401K retirement plan. If not, it is easy to set up an Individual Retirement Account through an online broker or a broker with a physical office location. 

    Remember, you can achieve financial wellness if you create a plan with realistic goals and timelines.  Review your plan often, hold yourself accountable, never give up, and you will achieve financial wellness. If you need help with unsecured debt, such as installment and payday loans, credit cards, cell phone and medical bills, contact Progressive Debt Relief by phone 877.590.1847 or through our contact form for a free consultation.